American Funds Model Portfolios in market uncertainty
3Q26 market commentary and model portfolio asset allocation
Samir Mathur
Chairman of the Portfolio Solutions Committee
Mario DiVito
Multi-Asset Investment Director
Stanley Moy
Multi-Asset Investment Director
Key takeaways for the quarter ended September 30, 2026
- Resilient corporate earnings and sustained investor enthusiasm for artificial intelligence (AI) kept stocks on an upward trajectory while heightened inflation and a Fed rate hike pushed interest rates higher across the curve, weighing on bond markets and dividend-oriented equity sectors like utilities.
- The American Funds® Model Portfolios all had negative absolute and relative returns for the quarter on both a gross and net-of-fees basis, with the exception of three tax-aware models that outpaced their benchmarks on a gross basis but lagged net of fees.
- The Portfolio Solutions Committee (PSC) and the Capital Solutions Group (CSG) monitor model portfolios regularly for risks and to maintain alignment with their long-term portfolio objectives. As a result, some of our tax-aware models were reallocated this quarter. At the underlying fund level, managers continue to use company- and security-specific research to make real-time decisions and identify timely opportunities in today’s ever-changing market environment.
Market review
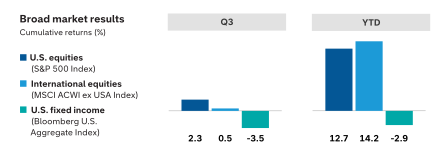
Equities rose and bond markets declined against a backdrop of resilient corporate earnings and sustained investor enthusiasm for AI amid elevated inflation expectations, increasing energy prices and rising rates. Among developed markets, U.S. and Japanese stocks posted the highest returns, while European equities declined. The S&P 500 Index returned approximately 2.3% for the quarter, reaching all-time highs in August. The MSCI All Country World (ACWI) ex USA Index grew by approximately 0.5%. Overall, value outpaced growth, with the Russell 1000 Value Index advancing 2.6% and the Russell 1000 Growth Index advancing 0.9%, although traditional dividend sectors trailed in a rising rate environment.
Within the S&P 500 Index, the energy sector posted the strongest gains, supported by higher oil prices amid supply disruptions related to the conflict in the Middle East. The technology sector posted solid gains overall, although the rapidly evolving AI narrative created volatility and uneven results among individual companies. In contrast, utilities fell sharply as rising bond yields pressured dividend-oriented investments. Industrials also declined, partly reflecting tariff-related cost pressures.
U.S. bonds fell, with the Bloomberg U.S. Aggregate Index declining 3.51%. The yield curve steepened, with two-year Treasury yields rising 71 basis points (bps) to 4.89% and 10-year Treasury yields rising 82 bps to 5.29%. In U.S. credit markets, investment-grade bonds (rated BBB/Baa and above) and high-yield debt weakened. Spreads to Treasuries increased by 6 bps to 80 bps for investment grade and by 41 bps to 311 bps for high yield (BB/Ba and below).
The U.S. Federal Reserve (Fed) raised its benchmark interest rate by 25 bps to a range of 3.75%–4.00% in September, the first hike in nearly three years. Fed Chair Kevin Warsh stated the decision was aimed at returning inflation to the central bank’s 2% objective. Further monetary tightening may be likely, with Fed policy projections showing 16 of 18 policymakers expect at least one additional 25-bp rate increase by the end of the year.
The European Central Bank (ECB) raised its key policy rate by 25 bps to 2.50% in September, marking its second hike this year. The decision came amid elevated inflation risks, as renewed shipping disruptions through the Strait of Hormuz tightened global supplies. Headline inflation rose to 3.8% in September from 3.2% in August and is projected to average 3.0% in 2026. Given the uncertain outlook, policymakers noted that future policy adjustment will be guided by incoming economic data and risk assessments.
Model portfolio results for Q3
All results are for the quarter unless otherwise specified.
American Funds Global Growth Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and greater exposure to industrials hurt relative results but was partially offset by less exposure to utilities and consumer staples.
- Geographic allocations to U.S. and non-U.S. equity ended the quarter at 49% and 48%, respectively.
- The Growth Fund of America® was the strongest returning underlying equity fund, while SMALLCAP World Fund® and The New Economy Fund® were two of the weakest.
American Funds Growth Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and greater exposure to industrials hurt relative results but was partially offset by less exposure to utilities and greater exposure to health care.
- The Growth Fund of America and The Investment Company of America were the strongest returning underlying equity funds, while SMALLCAP World Fund and The New Economy Fund were two of the weakest.
American Funds Moderate Growth Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and health care hurt relative results but was partially offset by security selection in consumer staples and greater exposure to health care.
- Fixed income was a source of relative strength, driven primarily by less exposure to the asset class. Emerging markets bonds, securitized debt and corporate bonds aided returns while Treasuries were the primary detractor.
- The Growth Fund of America and The Investment Company of America were the strongest returning underlying equity funds, while SMALLCAP World Fund and American Funds Global Insight Fund were two of the weakest.
American Funds Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and health care hurt relative results but was partially offset by security selection in consumer staples and greater exposure to health care.
- Fixed income was a source of relative strength, driven primarily by less exposure to the asset class. Securitized debt, emerging markets bonds and corporate bonds aided returns while Treasuries were the primary detractor.
- The Growth Fund of America was the strongest returning underlying fund, while SMALLCAP World Fund and American Funds Strategic Bond Fund were two of the weakest.
American Funds Moderate Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection was a detractor while non-U.S. equity security selection was additive.
- Security selection in information technology and health care hurt relative results but was partially offset by security selection in materials and greater exposure to energy.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Securitized debt, corporate bonds and emerging markets bonds aided returns while Treasuries were the primary detractor.
- The Growth Fund of America was the strongest returning underlying fund, while SMALLCAP World Fund and American Funds Strategic Bond Fund were two of the weakest.
American Funds Conservative Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection was a detractor while non-U.S. equity security selection was additive.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in information technology and greater exposure to utilities hurt relative results but was partially offset by greater exposure to energy and security selection in industrials.
- Fixed income was a source of relative strength, driven primarily by less exposure to the asset class. Securitized debt aided returns while Treasuries detracted.
- American Mutual Fund and The Bond Fund of America® were among the weakest funds for the quarter.
American Funds Conservative Income and Growth Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection detracted while non-U.S. security selection's impact was minimal.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in information technology and health care hurt relative results but was partially offset by greater exposure to energy and security selection in consumer staples.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Securitized debt aided returns while Treasuries detracted.
- American Balanced Fund® and American Funds Strategic Bond Fund were among the weakest funds for the quarter.
American Funds Conservative Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection detracted while non-U.S. security selection's impact was minimal.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in information technology and less exposure to the same sector hurt relative results but was partially offset by greater exposure to energy and security selection in consumer staples.
- Fixed income weighed on results, driven primarily by bond selection. Treasuries detracted while securitized debt aided returns.
- The Bond Fund of America and American Funds Strategic Bond Fund were among the weakest funds for the quarter.
American Funds Preservation Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- Negative results were primarily driven by bond selection. Treasuries detracted while securitized debt aided returns.
American Funds Retirement Income Model Portfolio – Enhanced produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection was a detractor while non-U.S. equity security selection was additive.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in information technology and health care hurt relative results but was partially offset by greater exposure to energy and security selection in industrials.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Corporate bonds and securitized debt aided returns while Treasuries were the primary detractor.
- International Growth and Income Fund was the strongest returning underlying fund, while The Bond Fund of America and American Funds Multi-Sector Income Fund were two of the weakest.
American Funds Retirement Income Model Portfolio – Moderate produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection was a detractor while non-U.S. equity security selection was additive.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection and less exposure in information technology hurt relative results but was partially offset by greater exposure to energy and security selection in industrials.
- Fixed income was a source of relative strength, driven primarily by less exposure to the asset class. Securitized debt and corporate bonds aided returns while Treasuries were the primary detractor.
- American Mutual Fund and U.S. Government Securities Fund® were among the weakest funds for the quarter.
American Funds Retirement Income Model Portfolio – Conservative produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. equity security selection was a detractor while non-U.S. equity security selection was additive.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection and less exposure in information technology hurt relative results but was partially offset by greater exposure to energy and security selection in industrials.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Securitized debt and corporate bonds aided returns while Treasuries were the primary detractor.
- American Mutual Fund and U.S. Government Securities Fund were among the weakest funds for the quarter.
American Funds Tax-Aware Moderate Growth Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and industrials hurt relative results but was partially offset by security selection in financials and communication services.
- Fixed income was a source of relative strength, driven primarily by less exposure to the asset class. Health care and housing bonds aided returns while special tax municipals were the primary detractor.
- Capital Group Growth ETF and Capital Group Core Equity ETF were the strongest returning underlying equity funds, while Capital Group U.S. Small and Mid Cap ETF and Capital Group Global Growth Equity ETF were two of the weakest.
American Funds Tax-Aware Moderate Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and greater exposure to industrials hurt relative results but was partially offset by security selection in financials and communication services.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Health care and housing bonds aided returns while special tax municipals were the primary detractor.
- Capital Group Core Equity ETF was the strongest returning underlying fund, while Capital Group U.S. Small and Mid Cap ETF and Capital Group Municipal High-Income ETF were two of the weakest.
American Funds Tax-Aware Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Security selection in information technology and greater exposure to industrials hurt relative results but was partially offset by security selection in financials and communication services.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Health care and housing bonds aided returns while special tax municipals were the primary detractor.
- Capital Group Growth ETF was the strongest returning underlying fund, while Capital Group U.S. Small and Mid Cap ETF and Capital Group Municipal High-Income ETF were two of the weakest.
American Funds Tax-Aware Conservative Growth and Income Model Portfolio produced negative absolute returns for the quarter and trailed its benchmark.
- U.S. and non-U.S. equity security selection were detractors.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in information technology and consumer discretionary hurt relative results but was partially offset by security selection in financials and communication services.
- Fixed income was a source of relative strength due to a combination of bond selection and positioning within the asset class. Housing and general obligation bonds aided returns while special tax municipals were the primary detractor.
- Capital Group Core Equity ETF was the strongest returning underlying fund, while Capital Group Municipal High-Income ETF and Capital Group Municipal Income ETF were two of the weakest.
American Funds Tax-Aware Moderate Income Model Portfolio produced negative absolute returns for the quarter but outpaced its benchmark on a gross basis while net returns lagged.
- U.S. and non-U.S. equity security selection were detractors.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in communication services and financials contributed positively while security selection in information technology and consumer discretionary detracted.
- Fixed income was a source of relative strength, driven primarily by bond selection in housing municipal bonds. Special tax municipal bonds slightly detracted.
- Capital Group Core Equity ETF was the strongest returning underlying fund, while Capital Group Municipal High-Income ETF and Capital Group Municipal Income ETF were two of the weakest.
American Funds Tax-Aware Conservative Income Model Portfolio produced negative absolute returns for the quarter but outpaced its benchmark on a gross basis while net returns lagged.
- U.S. equity security selection detracted while non-U.S. security selection's impact was minimal.
- Given the model's focus on income, a structural tilt toward dividend-paying equities served as a headwind to results.
- Security selection in communication services and greater exposure to energy contributed positively while security selection in information technology and consumer discretionary detracted.
- Fixed income was a source of relative strength, driven primarily by bond selection. Housing and health care aided returns while special tax was the primary detractor.
- Capital Group Core Equity ETF was the strongest returning underlying fund, while Capital Group Municipal High-Income ETF and Capital Group Municipal Income ETF were two of the weakest.
American Funds Tax-Exempt Preservation Model Portfolio produced negative absolute returns for the quarter but outpaced its benchmark on a gross basis while net returns lagged.
- Relative strength was driven primarily by bond selection in housing and general obligation municipal bonds while industrial development revenue municipal bonds detracted.
- Limited Term Tax-Exempt Bond Fund of America® was the weakest underlying fund for the quarter.
Effective September 30, 2026, American Funds Preservation Model Portfolio will be renamed to American Funds Preservation and Income Model Portfolio; American Funds Tax-Exempt Preservation Model Portfolio will be renamed to Capital Group ETF-MF Tax-Exempt Preservation and Income Model; American Funds Tax-Aware Moderate Growth Model Portfolio will be renamed to Capital Group ETF Tax-Aware Moderate Growth Model; American Funds Tax-Aware Moderate Growth and Income Model Portfolio will be renamed to Capital Group ETF Tax-Aware Moderate Growth and Income Model; American Funds Tax-Aware Growth and Income Model Portfolio will be renamed to Capital Group ETF Tax-Aware Growth and Income Model; American Funds Tax-Aware Moderate Income Model Portfolio will be renamed to Capital Group ETF Tax-Aware Moderate Income Model; American Funds Tax-Aware Conservative Growth and Income Model Portfolio will be renamed to Capital Group ETF Tax-Aware Conservative Growth and Income Model; and American Funds Tax-Aware Conservative Income Model Portfolio will be renamed to Capital Group ETF Tax-Aware Conservative Income Model.
What’s new in American Funds Model Portfolios’ asset allocation?
As part of the ongoing active management of our multi-asset solutions, the Portfolio Solutions Committee (PSC), with the help of the Capital Solutions Group (CSG), regularly conducts strategic and thematic research on the portfolios to maintain alignment with their long-term objectives. The team assessed current portfolio allocations utilizing updated capital markets output and model optimization, considering both quantitative and qualitative criteria. Following the most recent review, research-driven changes to several models have been approved and implemented.
Core model portfolios:
- Tax aware portfolios:
- Geographic mix: Increase non-U.S. equity exposure
- Improve geographic balance while seeking to benefit from broadening global markets and a potentially weaker U.S. dollar regime.
- Add allocation to CGIC – Capital Group International Core Equity ETF for fund diversification and to seek international growth and dividend-oriented exposure.
- Increase emerging markets exposure in more growth-oriented models.
- Reduce home bias in conservative models with dividend-oriented global equities.
- Equity-style diversification:
- Slightly increase growth equity exposure to pursue modestly more capital appreciation and core-oriented positioning.
- Geographic mix: Increase non-U.S. equity exposure
Looking ahead
Although corporate earnings have generally remained resilient, there is a high degree of geopolitical and economic uncertainty in markets. Inflation has moderated from earlier highs but remains elevated relative to central bank targets, prompting the Federal Reserve to raise interest rates during the quarter and indicate the likelihood of at least one more hike in 2026. At the same time, ongoing tensions in the Middle East continue to create uncertainty around energy prices, inflation and global growth. Against this backdrop, underlying fund managers will continue to look for companies with attractive valuations, durable business models and quality management teams.
While AI-related companies continue to account for a significant share of equity market gains, their sizable weights within U.S. and emerging markets indexes have heightened concentration risk, making security selection increasingly important within active strategies. Underlying fund managers strive to pursue superior long-term outcomes on a risk-adjusted basis through diversification while balancing fund objectives.
Within equities, health care remains an area of interest, as select companies with innovative product pipelines and multiple potential growth drivers may be less dependent on any single product or market trend. Managers also continue to find opportunities in industrials, including electrical equipment, machinery and other businesses that support ongoing investment in AI-related infrastructure. In addition, underlying fund managers are seeking opportunities among companies whose shares have lagged amid the market’s focus on AI despite strong fundamentals and attractive long-term prospects.
Within core U.S. fixed income portfolios, underlying fund managers continue to view higher quality bonds as an attractive and cost-effective source of potential downside protection, particularly as higher yields have improved prospective return potential. Managers also see value in select areas of the securitized market, including asset-backed securities (ABS) and agency mortgage-backed securities (MBS), where security selection may uncover attractive risk-adjusted opportunities. Within credit, where valuations remain tight, managers are emphasizing higher quality, less economically sensitive issuers with adequate compensation for risk. Additionally, managers will continue seeking opportunities beyond traditional benchmark sectors, leveraging their ability to research across a broad range of credit markets.
Investments are not FDIC–insured, nor are they deposits of or guaranteed by a bank or any other entity, so they may lose value.
Investors should carefully consider investment objectives, risks, charges and expenses. This and other important information is contained in the fund prospectuses and summary prospectuses, which can be obtained from a financial professional and should be read carefully before investing.
Capital Group exchange-traded funds (ETFs) are actively managed and do not seek to replicate a specific index. ETF shares are bought and sold through an exchange at the then current market price, not net asset value (NAV), and are not individually redeemed from the fund. Shares may trade at a premium or discount to their NAV when traded on an exchange. Brokerage commissions will reduce returns. There can be no guarantee that an active market for ETFs will develop or be maintained, or that the ETF's listing will continue or remain unchanged.
Model portfolios are only available through registered investment advisers. This content is intended for registered investment advisers and their clients.
Results as of September 30, 2026. Past results are not predictive of results in future periods. Current and future results may be lower or higher than those shown. Prices and returns will vary, so investors may lose money. Investing for short periods makes losses more likely. For current information and month–end results, visit capitalgroup.com. Composite returns reflect changes, if any, in the underlying fund allocations over the model’s lifetime. Underlying funds may have been added or removed during a model’s lifetime. Rebalancing is performed in accordance with the investment adviser’s strategic asset allocation views for the model. Please refer to capitalgroup.com/advisor/investments/ model-portfolios.htm for historical underlying fund allocations. Composite net results are calculated by subtracting an annual 3% fee, (which is equal to or higher than the highest actual model portfolio wrap fee charged by a program sponsor) from the gross composite monthly returns, which are net of underlying mutual fund fees and expenses. Composite gross results are net of underlying mutual fund fees and expenses and gross of any advisory fees charged by model providers. Results would have been lower if such fees had been deducted. Results and results-based figures shown are preliminary and subject to change.
Advisory services offered through Capital Research and Management Company (CRMC) and its RIA affiliates.
Contribution to returns commentary is based on representative accounts of the model composites and is net of all fees and expenses applicable to the underlying funds and gross of any advisory fee charged by model providers. The net of fees composite results shown illustrate the impact of fees on the portfolio. Attribution for underlying ETFs is based on market price.
Investment results assume all distributions are reinvested and reflect applicable fees and expenses. Returns for one year or less are not annualized, but calculated as cumulative total returns.
When applicable, investment results reflect fee waivers and/or expense reimbursements, without which results would have been lower. Read details about how waivers and/or reimbursements affect the results for each fund. View results and yields without fee waiver and/or expense reimbursement.
There may have been periods when the results lagged the index(es). Certain market indexes are unmanaged, and, therefore, have no expenses. Investors cannot invest directly in an index.
Model portfolios are subject to the risks associated with the underlying funds in the model portfolio. Investors should carefully consider investment objectives, risks, fees and expenses of the funds in the model portfolio, which are contained in the fund prospectuses. Investing outside the United States involves risks, such as currency fluctuations, periods of illiquidity and price volatility. These risks may be heightened in connection with investments in developing countries. Small-company stocks entail additional risks, and they can fluctuate in price more than larger company stocks. The return of principal for bond funds and for funds with significant underlying bond holdings is not guaranteed. Fund shares are subject to the same interest rate, inflation and credit risks associated with the underlying bond holdings. Lower rated bonds are subject to greater fluctuations in value and risk of loss of income and principal than higher rated bonds. Investments in mortgage-related securities involve additional risks, such as prepayment risk. The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional cash securities, such as stocks and bonds.
A nondiversified fund has the ability to invest a larger percentage of assets in securities of individual issuers than a diversified fund. As a result, a single issuer could adversely affect a nondiversified fund’s results more than if the fund invested a smaller percentage of assets in securities of that issuer. See the applicable prospectus for details.
Bond ratings, which typically range from AAA/Aaa (highest) to D (lowest), are assigned by credit rating agencies such as Standard & Poor's, Moody's and/or Fitch, as an indication of an issuer's creditworthiness. If agency ratings differ, the security will be considered to have received the highest of those ratings, consistent with the portfolio's investment policies. Securities in the Unrated category have not been rated by a rating agency; however, the investment adviser performs its own credit analysis and assigns comparable ratings that are used for compliance with applicable investment policies.
For more information about the risks associated with each investment, go to its detailed information page or read the prospectus, if applicable.
Portfolios are managed, so holdings will change.
Model portfolios are provided to financial intermediaries who may or may not recommend them to clients. These portfolios consist of an allocation of funds for investors to consider and are not intended to be investment recommendations. The portfolios are asset allocations designed for individuals with different time horizons investment objectives and risk profiles. Allocations may change and may not achieve investment objectives. If a cash allocation is not reflected in a model, the intermediary may choose to add one. Capital Group does not have investment discretion or authority over investment allocations in client accounts. Investors should talk to their financial professional for information on other investment alternatives that may be available. In making investment decisions, investors should consider their other assets, income, and investments. Visit capitalgroup.com for current allocations.
The underlying funds for each model portfolio as of September 30, 2026, are as follows (allocations may not equal 100% due to rounding):
American Funds Global Growth Model Portfolio: Growth (83%): New Perspective Fund 20%, SMALLCAP World Fund 15%, The Growth Fund of America 13%, EUPAC Fund 10%, New World Fund 10%, The New Economy Fund 10%, American Funds Global Insight Fund 5%; Growth and income (17%): Capital World Growth and Income Fund 17%.
American Funds Growth Model Portfolio: Growth (75%): The Growth Fund of America 21%, New Perspective Fund 15%, SMALLCAP World Fund 15%, AMCAP Fund 10%, The New Economy Fund 10%, New World Fund 4%; Growth and income (25%): Fundamental Investors 10%, The Investment Company of America 10%, Washington Mutual Investors Fund 5%.
American Funds Moderate Growth Model Portfolio: Growth (39%): The Growth Fund of America 15%, SMALLCAP World Fund 10%, AMCAP Fund 5%, American Funds Global Insight Fund 5%, New World Fund 4%; Growth and income (33%): Capital World Growth and Income Fund 15%, The Investment Company of America 8%, Fundamental Investors 5%, Washington Mutual Investors Fund 5%; Balanced (26%): American Balanced Fund 13%, American Funds Global Balanced Fund 13%; Income (2%): American Funds Emerging Markets Bond Fund 2%.
American Funds Growth and Income Model Portfolio: Growth (21%): SMALLCAP World Fund 8%, American Funds Global Insight Fund 5%, The Growth Fund of America 5%, New World Fund 3%; Growth and income (42%): Capital World Growth and Income Fund 15%, The Investment Company of America 12%, Washington Mutual Investors Fund 10%, Fundamental Investors 5%; Equity income (10%): Capital Income Builder 10%; Balanced (10%): American Balanced Fund 10%; Income (17%): American Funds Multi-Sector Income Fund 5%, American Funds Strategic Bond Fund 5%, The Bond Fund of America 5%, American Funds Emerging Markets Bond Fund 2%.
American Funds Moderate Growth and Income Model Portfolio: Growth (15%): New Perspective Fund 5%, SMALLCAP World Fund 5%, The Growth Fund of America 3%, New World Fund 2%; Growth and income (22%): Washington Mutual Investors Fund 12%, Capital World Growth and Income Fund 10%; Equity income: (10%): The Income Fund of America 10%; Balanced (36%): American Balanced Fund 21%, American Funds Global Balanced Fund 15%; Income (17%): American Funds Multi-Sector Income Fund 5%, American Funds Strategic Bond Fund 5%, The Bond Fund of America 5%, American Funds Emerging Markets Bond Fund 2%.
American Funds Conservative Growth and Income Model Portfolio: Growth and income (26%): Washington Mutual Investors Fund 10%, Capital World Growth and Income Fund 9%, American Mutual Fund 7%; Equity income (30%): Capital Income Builder 15%, The Income Fund of America 15%; Income (44%): American Funds Multi-Sector Income Fund 15%, The Bond Fund of America 15%, American High-Income Trust 10%, American Funds Emerging Markets Bond Fund 4%.
American Funds Conservative Income and Growth Model Portfolio: Growth and income (20%): American Mutual Fund 13%, Capital World Growth and Income Fund 7%; Equity income (9%): The Income Fund of America 5%, Capital Income Builder 4%; Balanced (15%): American Balanced Fund 10%, American Funds Global Balanced Fund 5%; Income (56%): The Bond Fund of America 19%, American Funds Multi-Sector Income Fund 14%, American Funds Strategic Bond Fund 10%, Intermediate Bond Fund of America 10%, American Funds Emerging Markets Bond Fund 3%.
American Funds Conservative Income Model Portfolio: Growth and income (10%): American Mutual Fund 8%, Capital World Growth and Income Fund 2%; Equity income (10%): The Income Fund of America 6%, Capital Income Builder 4%; Balanced (5%): American Balanced Fund 5%; Income (75%): Intermediate Bond Fund of America 25%, The Bond Fund of America 20%, Short-Term Bond Fund of America 15%, American Funds Strategic Bond Fund 8%, American Funds Multi-Sector Income Fund 5%, American Funds Emerging Markets Bond Fund 2%.
American Funds Preservation Model Portfolio: Income (100%): Short-Term Bond Fund of America 55%, Intermediate Bond Fund of America 45%.
American Funds Retirement Income Model Portfolio — Enhanced: Growth (5%): AMCAP Fund 5%; Growth and income (15%): Capital World Growth and Income Fund 6%, American Mutual Fund 5%, International Growth and Income Fund 4%; Equity income (36%): Capital Income Builder 20%, The Income Fund of America 16%; Balanced (25%): American Balanced Fund 20%, American Funds Global Balanced Fund 5%; Income (19%): American Funds Multi-Sector Income Fund 9%, American High-Income Trust 5%, The Bond Fund of America 5%.
American Funds Retirement Income Model Portfolio — Moderate: Growth and income (12%): Capital World Growth and Income Fund 7%, American Mutual Fund 5%; Equity income (38%): The Income Fund of America 20%, Capital Income Builder 18%; Balanced (20%): American Balanced Fund 15%, American Funds Global Balanced Fund 5%; Income (30%): American Funds Multi-Sector Income Fund 9%, The Bond Fund of America 8%, U.S. Government Securities Fund 7%, American Funds Strategic Bond Fund 6%.
American Funds Retirement Income Model Portfolio — Conservative: Growth and income (7%): American Mutual Fund 7%; Equity income (33%): Capital Income Builder 18%, The Income Fund of America 15%; Balanced (12%): American Balanced Fund 8%, American Funds Global Balanced Fund 4%; Income (48%): The Bond Fund of America 15%, Intermediate Bond Fund of America 10%, American Funds Multi-Sector Income Fund 8%, American Funds Strategic Bond Fund 5%, American Funds Inflation Linked Bond Fund 5%, U.S. Government Securities Fund 5%.
American Funds Tax-Aware Moderate Growth Model Portfolio: Growth (67%): CGGE – Capital Group Global Equity ETF 20%, CGGR – Capital Group Growth ETF 18%, CGGO – Capital Group Global Growth Equity ETF 12%, CGMM – Capital Group U.S. Small and Mid Cap ETF 10%, CGNG – Capital Group New Geography Equity ETF 7%; Growth and income (21%): CGUS – Capital Group Core Equity ETF 18%, CGIC – Capital Group International Core Equity ETF 3%; Tax exempt (12%): CGHM – Capital Group Municipal High-Income ETF 6%, CGMU – Capital Group Municipal Income ETF 6%.
American Funds Tax-Aware Growth and Income Model Portfolio: Growth (44%): CGGE – Capital Group Global Equity ETF 15%, CGGO – Capital Group Global Growth Equity ETF 10%, CGMM – Capital Group U.S. Small and Mid Cap ETF 8%, CGGR – Capital Group Growth ETF 6%, CGNG – Capital Group New Geography Equity ETF 5%; Growth and income (33%): CGUS – Capital Group Core Equity ETF 16%, CGDV – Capital Group Dividend Value ETF 9%, CGDG – Capital Group Dividend Growers ETF 5%, CGIC – Capital Group International Core Equity ETF 3%; Tax-exempt (23%): CGMU – Capital Group Municipal Income ETF 13%, CGHM – Capital Group Municipal High-Income ETF 10%.
American Funds Tax-Aware Moderate Growth and Income Model Portfolio: Growth (31%): CGGE – Capital Group Global Equity ETF 14%, CGGO – Capital Group Global Growth Equity ETF 8%, CGMM – Capital Group U.S. Small and Mid Cap ETF 5%, CGNG – Capital Group New Geography Equity ETF 4%; Growth and income (36%): CGUS – Capital Group Core Equity ETF 14%, CGDV – Capital Group Dividend Value ETF 13%, CGDG – Capital Group Dividend Growers ETF 7%, CGIC – Capital Group International Core Equity ETF 2%; Tax-exempt (33%): CGHM – Capital Group Municipal High-Income ETF 18%, CGMU – Capital Group Municipal Income ETF 15%.
American Funds Tax-Aware Conservative Growth and Income Model Portfolio: Growth (9%): CGGE – Capital Group Global Equity ETF 9%; Growth and income (40%): CGDG – Capital Group Dividend Growers ETF 15%, CGDV – Capital Group Dividend Value ETF 13%, CGCV – Capital Group Conservative Equity ETF 5%, CGUS – Capital Group Core Equity ETF 5%, CGIC – Capital Group International Core Equity ETF 2%; Tax-exempt (51%): CGHM – Capital Group Municipal High-Income ETF 25%, CGMU – Capital Group Municipal Income ETF 22%, CGSM – Capital Group Short Duration Municipal Income ETF 4%.
American Funds Tax-Aware Moderate Income Model Portfolio: Growth (8%): CGGE – Capital Group Global Equity ETF 8%; Growth and income (29%): CGDV – Capital Group Dividend Value ETF 11%, CGDG – Capital Group Dividend Growers ETF 9%, CGCV – Capital Group Conservative Equity ETF 5%, CGUS – Capital Group Core Equity ETF 4%; Tax-exempt (63%): CGHM – Capital Group Municipal High-Income ETF 25%, CGMU – Capital Group Municipal Income ETF 25%, CGSM – Capital Group Short Duration Municipal Income ETF 13%.
American Funds Tax-Aware Conservative Income Model Portfolio: Growth (3%): CGGE – Capital Group Global Equity ETF 3%; Growth and income (18%): CGCV – Capital Group Conservative Equity ETF 7%, CGDG – Capital Group Dividend Growers ETF 5%, CGUS – Capital Group Core Equity ETF 3%, CGDV – Capital Group Dividend Value ETF 3%; Tax exempt (79%): CGSM – Capital Group Short Duration Municipal Income ETF 34%, CGMU – Capital Group Municipal Income ETF 30%, CGHM – Capital Group Municipal High-Income ETF 15%.
American Funds Tax-Exempt Preservation Model Portfolio: Tax-exempt (100%): Limited Term Tax- Exempt Bond Fund of America 40%, American Funds Short-Term Tax-Exempt Bond Fund 30%, CGSM – Capital Group Short Duration Municipal Income ETF 30%..
Model portfolio index/index blends
Index/Index blends for American Funds Model Portfolios are those that the Portfolio Solutions Committee believes most closely approximate the investment universe of a given model portfolio. The index/index blends do not specifically represent the benchmarks of the underlying funds in the American Funds model portfolios. The index/index blends for the model portfolios are a composite of the cumulative total returns for the indexes and respective weightings listed:
Global Growth — MSCI ACWI.
Growth — Index Blend: 75% S&P 500 and 25% MSCI ACWI ex USA indexes.
Moderate Growth — Index Blend: 60% S&P 500, 25% MSCI ACWI ex USA and 15% Bloomberg U.S. Aggregate indexes.
Growth and Income — Index Blend: 50% S&P 500, 25% MSCI ACWI ex USA and 25% Bloomberg U.S. Aggregate indexes.
Moderate Growth and Income — Index Blend: 45% S&P 500, 35% Bloomberg U.S. Aggregate and 20% MSCI ACWI ex USA indexes.
Conservative Growth and Income — Index Blend: 35% Bloomberg U.S. Aggregate, 30% S&P 500, 20% Bloomberg U.S. Corporate High Yield 2% Issuer Capped and 15% MSCI ACWI ex USA indexes.
Conservative Income and Growth — Index Blend: 55% Bloomberg U.S. Aggregate, 25% S&P 500, 10% Bloomberg U.S. Corporate High Yield 2% Issuer Capped and 10% MSCI ACWI ex USA indexes.
Conservative Income — Index blend: 45% Bloomberg U.S. Aggregate Index, 35% Bloomberg 1-5 Year U.S. Government/Credit A+, 15% S&P 500 and 5% MSCI ACWI ex USA indexes.
Preservation — Bloomberg 1-5 Year U.S. Government/Credit A+ Index.
Tax-Aware Moderate Growth — Index Blend: 60% S&P 500, 25% MSCI ACWI ex USA and 15% Bloomberg Municipal Bond indexes.
Tax-Aware Growth and Income — Index Blend: 50% S&P 500, 25% Bloomberg Municipal Bond and 25% MSCI ACWI ex USA indexes.
Tax-Aware Moderate Growth and Income — Index Blend: 45% S&P 500, 35% Bloomberg Municipal Bond and 20% MSCI ACWI ex USA indexes.
Tax-Aware Conservative Growth and Income — Index Blend: 40% Bloomberg Municipal Bond, 30% S&P 500, 15% Bloomberg Municipal Bond: High Yield and 15% MSCI ACWI ex USA indexes.
Tax-Aware Moderate Income — Index blend: 55% Bloomberg Municipal Bond, 25% S&P 500, 10% MSCI ACWI ex USA and 10% Bloomberg Municipal Bond: High Yield indexes.
Tax-Aware Conservative Income — Index blend: 40% Bloomberg Municipal Bond, 40% Bloomberg Municipal Bond 1-7 Year Blend, 15% S&P 500 and 5% MSCI ACWI ex USA indexes
Tax-Exempt Preservation — Bloomberg Municipal Bond 1-7 Year Blend.
Retirement Income — Enhanced — Index Blend: 40% S&P 500, 40% Bloomberg U.S. Aggregate and 20% MSCI ACWI ex USA indexes.
Retirement Income — Moderate — Index Blend: 50% Bloomberg U.S. Aggregate, 35% S&P 500 and 15% MSCI ACWI ex USA indexes.
Retirement Income — Conservative — Index Blend: 65% Bloomberg U.S. Aggregate, 25% S&P 500 and 10% MSCI ACWI ex USA indexes.
The index blends are rebalanced monthly. MSCI index results reflect dividends gross of withholding taxes through 12/31/00 and dividends net of withholding taxes thereafter. The indexes are unmanaged, and their results include reinvested dividends and/or distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. Investors cannot invest directly in an index. There have been periods when the model portfolio has lagged the index/index blend.
All Capital Group trademarks mentioned are owned by The Capital Group Companies, Inc., an affiliated company or fund. All other company and product names mentioned are the property of their respective companies.
S&P 500 Index is a market capitalization-weighted index based on the results of approximately 500 widely held common stocks.
The S&P 500 Index is a product of S&P Dow Jones Indices LLC and/or its affiliates and has been licensed for use by Capital Group. Copyright © 2026 S&P Dow Jones Indices LLC, a division of S&P Global, and/or its affiliates. All rights reserved. Redistribution or reproduction in whole or in part is prohibited without written permission of S&P Dow Jones Indices LLC.
MSCI All Country World ex USA Index is a free float-adjusted market capitalization weighted index that is designed to measure equity market results in the global developed and emerging markets, excluding the United States. The index consists of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter.
MSCI USA Index is a free float-adjusted, market capitalization-weighted index that is designed to measure the U.S. portion of the world market. This index is unmanaged and includes reinvested dividends and/or distributions, but does not reflect sales charges, commissions, expenses, or taxes. Results reflect dividends gross of withholding taxes.
Source: MSCI. The MSCI information may only be used for your internal use, may not be reproduced or redisseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to compiling, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages. Please refer to the data provider's website for more information.
Bloomberg U.S. Aggregate Index represents the U.S. investment-grade fixed-rate bond market.
Bloomberg U.S. Corporate High Yield Index covers the universe of fixed-rate, non-investment-grade debt.
Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non- investment-grade debt. The index limits the maximum exposure of any one issuer to 2%.
The Bloomberg Municipal Bond: High Yield Index is a flagship measure of the U.S. municipal tax-exempt non-investment grade bond market. Included in the index are securities from all 50 U.S. States and four other qualifying regions (Washington D.C., Puerto Rico, Guam, and the Virgin Islands). The index includes state and local general obligation bonds and revenue bonds. All bonds in the Index are tax exempt and hence are not eligible for other indices that include taxable high yield bonds, such as the U.S. High Yield Index and EM USD Aggregate Index.
Bloomberg Municipal Bond Index is a market-value-weighted index designed to represent the long-term investment-grade tax-exempt bond market.
Bloomberg U.S. Government/Credit 1-3 Years ex BBB Index is a market-value weighted index that tracks the total return results of fixed-rate, publicly placed, dollar-denominated obligations issued by the U.S. Treasury, U.S. government agencies, quasi-federal corporations, corporate or foreign debt guaranteed by the U.S. government, and U.S. corporate and foreign debentures and secured notes that meet specified maturity, liquidity and quality requirements, with maturities of one to three years, excluding BBB-rated securities.
Bloomberg Municipal Bond 1-7 Year Blend Index is a market-value-weighted index that includes investment-grade tax-exempt bonds with maturities of one to seven years.
Bloomberg 1-5 Year U.S. Government/Credit A+ Index is a market-value weighted index that tracks the total return results of fixed-rate, publicly placed, dollar-denominated obligations issued by the U.S. Treasury, U.S. government agencies, quasi-federal corporations, corporate or foreign debt guaranteed by the U.S. government, and U.S. corporate and foreign debentures and secured notes that meet specified maturity, liquidity and quality requirements, with maturities of one to five years, including A- rated securities and above.
Bloomberg Index Services Limited. BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg or Bloomberg’s licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg’s licensors approves or endorses this material or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
Russell 1000 Index is a market capitalization-weighted index that represents the top 1,000 stocks in the U.S. equity market by market capitalization.
Russell 1000 Growth Index is a market capitalization-weighted index that represents the large-cap growth segment of the U.S. equity market and includes stocks from the Russell 1000 Index that have higher price-to-book ratios and higher expected growth values.
Russell 1000 Value Index is a market capitalization-weighted index that represents the large-cap value segment of the U.S. equity market and includes stocks from the Russell 1000 Index that have lower price-to-book ratios and lower expected growth values.
Russell 2000 Index is a widely followed stock market index that measures the performance of approximately 2,000 small-cap publicly traded U.S. companies.
FTSE/Russell indexes: London Stock Exchange Group plc and its group undertakings (collectively, the “LSE Group”). © LSE Group 2026. FTSE Russell is a trading name of certain of the LSE Group companies. FTSE indexes are trademarks of the relevant LSE Group companies and are used by any other LSE Group company under license. All rights in the FTSE Russell indexes or data vest in the relevant LSE Group company which owns the index or the data. Neither LSE Group nor its licensors accept any liability for any errors or omissions in the indexes or data and no party may rely on any indexes or data contained in this communication. No further distribution of data from the LSE Group is permitted without the relevant LSE Group company’s express written consent. The LSE Group does not promote, sponsor or endorse the content of this communication.
Capital market assumptions are long-term projections of the future performance of asset class returns based on their respective benchmark indexes or other proxies that incorporate analysis and observations. This analysis represents the views of a small group of investment professionals based on their individual research and are approved by the Capital Market Assumptions Oversight Committee. They should not be interpreted as the view of Capital Group as a whole. As Capital Group employs The Capital System, the views of other individual analysts and portfolio managers may differ from those presented here. They are provided for informational purposes only and are not intended to provide any assurance or promise of actual returns. They reflect long-term projections of asset class returns and are based on the respective benchmark indexes, or other proxies, and therefore do not include any outperformance gain or loss that may result from active portfolio management. Note that the actual results will be affected by any adjustments to the mix of asset classes. All market forecasts are subject to a wide margin of error.
Statements attributed to an individual represent the opinions of that individual as of the date published and do not necessarily reflect the opinions of Capital Group or its affiliates. This information is intended to highlight issues and should not be considered advice, an endorsement or a recommendation.
This content, developed by Capital Group, home of American Funds, should not be used as a primary basis for investment decisions and is not intended to serve as impartial investment or fiduciary advice.
All Capital Group trademarks mentioned are owned by The Capital Group Companies, Inc., an affiliated company or fund. All other company and product names mentioned are the property of their respective companies.
Use of this website is intended for U.S. residents only.