Election
 Matt Miller
 Tom Cooney
 Talha Khan
Don't miss our latest insights.
In the aftermath of the U.S. midterm elections, a big blue wave of Democratic Party victories has raised important questions about three critical issues central to the U.S. economy and markets.
How will the coming sea change in American politics affect the artificial intelligence boom, global trade deals and the outcome of the Iran war? The American people have spoken at the ballot box, but how will that sentiment translate into real-world events? Three of Capital Group’s most experienced policy advisors offer their views.
The politics around AI data centers will improve
Matt Miller, political economist
Given the sharp selloff in AI-related stocks last week, you may be surprised to learn that I think the political backlash against data centers will ease, not worsen, in the year ahead. That doesn’t mean there won’t be a lot of noise along the way, and some near-term delays, but my hypothesis is that although the costs of the data center buildout will rise, the quantity of compute sought will be politically achievable once new leaders settle in to govern.
What leads me to this emerging view? The coalition behind the data center buildout knows it has fundamentally botched the politics on this issue and is moving aggressively to fix it. Based on what I’ve learned speaking with AI executives, investors and political strategists, it’s clear they are working together to come forward with a new framework of more generous, responsible and transparent offers to communities affected by data center construction. The commitments may include: no impact on water supply and quality; no impact on utility rates, along with a readiness to throttle energy use if needed at times of peak demand; and appropriate protections against excessive noise and environmental impacts. Beyond that, there may be a need for tax contributions or related investments that assure an unambiguously positive influence on communities.
Four potential paths in the AI data center buildout story
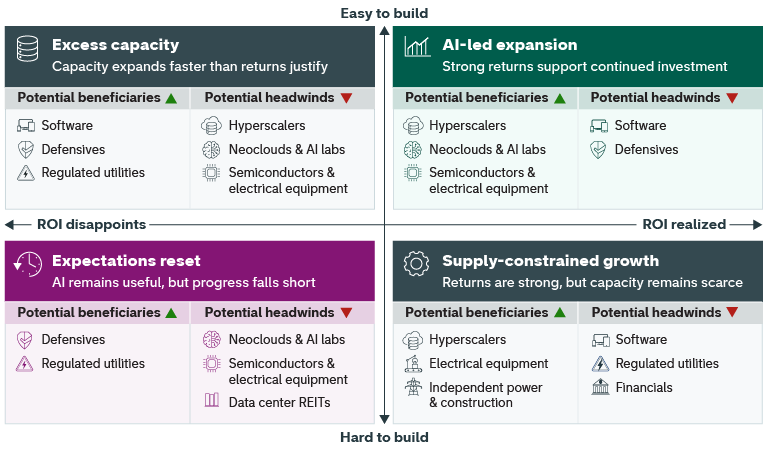
Source: Capital Group. Scenarios reflect analysis of Capital Group’s Night Watch team as of October 2026, and they are not predictive of future outcomes. ROI: return on investment. REITs: real estate investment trusts. Hyperscalers are large-scale cloud service providers that offer computing power and storage to organizations and individuals globally. Neoclouds are specialized cloud infrastructure providers dedicated to AI workloads.
As new benefits from the pro-data center coalition become clearer, I believe public opinion will shift. All the pre-election calls for moratoriums have been politically sufficient, yet ultimately flexible, positions for officials of both parties to take as community opposition has risen. It shows voters they are being heard, but it also leaves the door open for win-win negotiations to proceed in states with new leaders, such as Texas, Ohio and Georgia.
A year from now, I believe this will be a big piece of the data center construction story. From an elected official’s standpoint, the positioning is excellent. They can show toughness by pushing back against big tech firms that voters don’t trust — and then deliver serious protections and broader community benefits for which they can take credit. This may result in higher costs for AI development. I would urge investors not to overreact to short-term political noise, particularly when you see tech executives called before Congress or even investigated. Beyond the headlines and given some time for a new political narrative to take shape, the puck is in the process of moving to a better long-term place for the data center buildout.
U.S. trade leverage waning post-midterms
Tom Cooney, international policy advisor
For the next two years while President Trump remains in the White House, other countries — friend and foe — will be recalculating their relationships and leverage with Washington, D.C. My base case is that we will see more pushback from abroad and even harder bargaining on trade and tariffs, but not a total break with Trump because he can still inflict damage in a trade-war scenario.
China will prioritize “constructive strategic stability” as its primary objective for the next two years, continue de-risking from the U.S., and will not seek any “grand bargain” that could well expire in 2028. Canada, Brazil and India will feel even more emboldened to resist overly generous trade concessions. They would prefer deals and stability, but their leaders will be rewarded at home for hanging tough against Trump.
U.S. tariff revenue has declined from its peak early last year
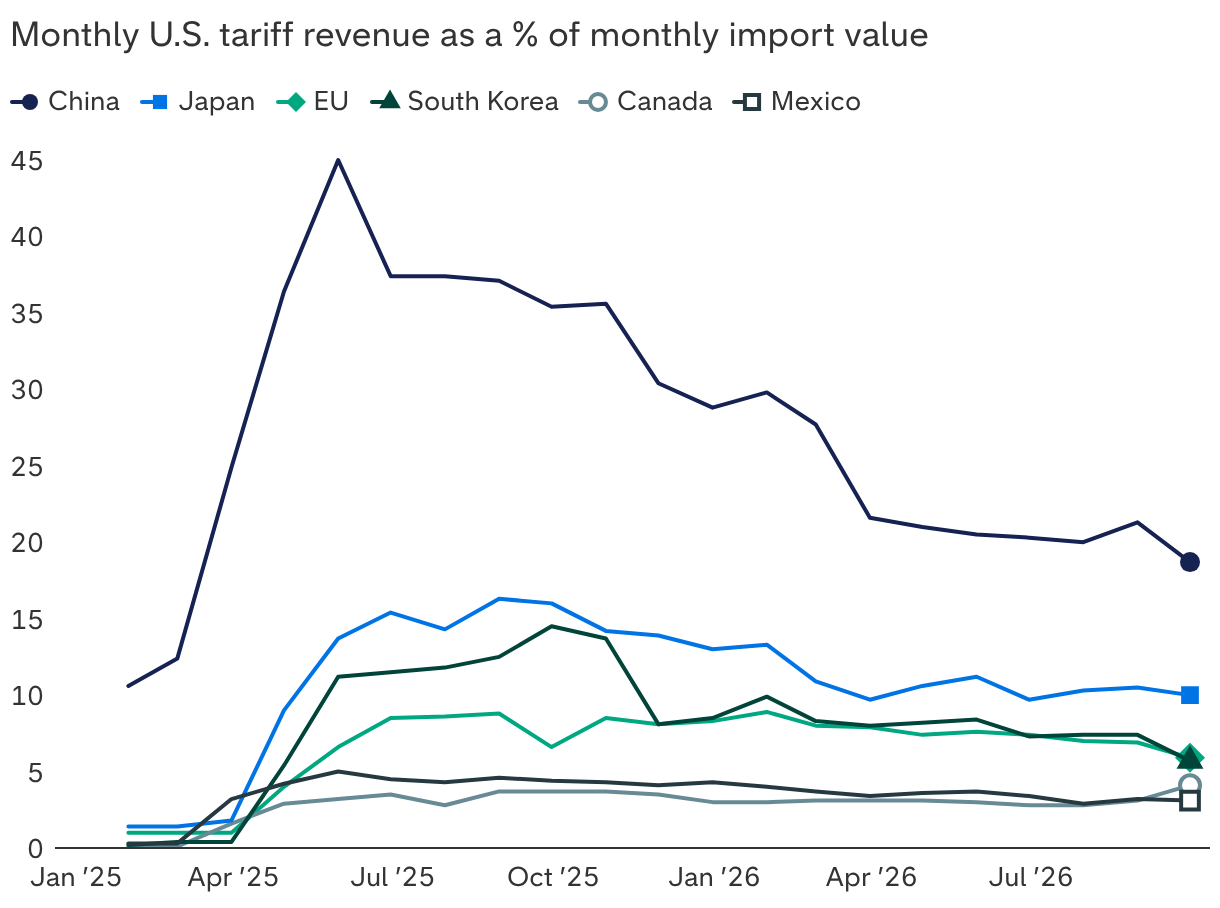
Sources: Capital Group, Peterson Institute for International Economics (PIIE), U.S. International Trade Commission (USITC). Figures reflect PIIE calculations using USITC data. Total import value includes cost, insurance and freight. As of September 30, 2026.
Japan, South Korea and Europe will seek to avoid trade conflict, but I am now even more skeptical than I already was that they will actually deliver anything close to the exorbitant investment levels they agreed to in earlier trade deals with the U.S. They will make some investments in the U.S., of course, because it remains a good place to invest with many viable projects offering good returns. But I would not count on the European Union to deliver anything like the previously agreed $600 billion or Japan to deliver $550 billion by end of 2028, for example.
In my view, the lesson from the U.S. midterm elections, as well as the 2024 general election, is that the American public is taking turns punishing political parties for their failure to deliver what matters most — fixing problems at home of inflation, affordability and economic opportunity. The 2024 election did not signal a permanent right-wing realignment, nor does last week’s “blue tsunami” signal the same for left-leaning political leadership. Neither party owns the electorate, and American voters are identifying less with either party.
The only certainty is that we are nearing the end of the Trump era, and he will resist losing primacy as he now must contend with a Democratic Congress. This dynamic sets the stage for further contention and volatility ahead. I expect President Trump will be more restrained than ever domestically by the courts and Congress, so this will cause him — like many presidents in the final two years of the second term — to lean into foreign policy where he has more leeway, as well as legacy projects seeking to leave his physical mark on Washington landmarks.
Ending the Iran war won’t be easy or quick
Talha Khan, political economist
The U.S. midterms have reduced the immediate risk of another American attack on Iran, but they may have made the war harder to end. The political costs of renewed escalation have risen for President Trump, making it more attractive to maintain economic and military pressure while giving diplomacy more time. But the election has also complicated the search for an exit. Washington and Tehran remain locked in a game of cat and mouse. Neither side wants to offer concessions that could hand the other a strategic victory. The problem, as always, is not whether both sides ultimately want an exit, but how we get there.
What has changed this week is the immediate risk of deliberate U.S. escalation. That risk has fallen, but it is certainly not zero. Following Trump’s conversation with the Qatari prime minister, another round of U.S. strikes no longer appears to be the immediate base case. Trump has explicitly kept the military option open, but for now appears to have concluded that the uncertain benefits of another round of strikes do not justify the military, economic and political costs.
Instead, Trump appears to have chosen economic pressure over military escalation, at least for now. The launch of “Operation Iron Gate” points to an effort to tighten the Iran blockade further, constrain its ability to export oil and allow that pressure to accumulate, while keeping substantial U.S. military power in the region as a credible threat. That also buys more time for diplomacy. If talks progress, Trump can argue that maximum pressure forced Tehran back to the table. If they fail, the military option remains available.
The U.S.-Iran conflict has sparked a sharp rise in oil prices
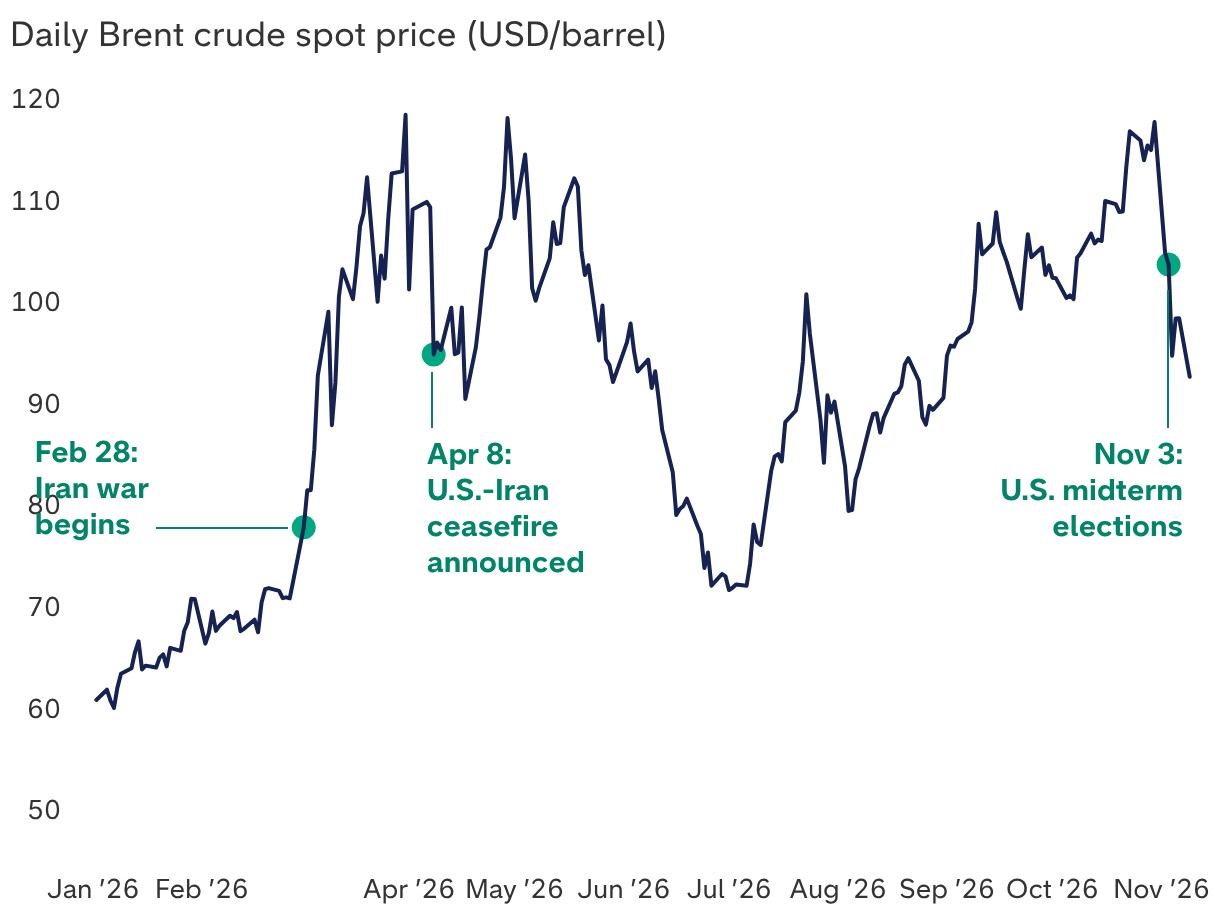
Sources: Capital Group, Bloomberg, ICE, Reuters. As of November 9, 2026.
However, the absence of an immediate U.S. strike should not be confused with de-escalation. Iran’s response since Trump’s announcement suggests very little willingness to soften its existing negotiating position. If anything, the midterms appear to have strengthened Tehran’s belief that time is working in its favor. Iran does not need to defeat the U.S. militarily if it can survive, refuse to capitulate and impose enough economic and political costs that Washington eventually loses the appetite to continue.
That creates a central problem: Washington may prefer the status quo, but Tehran does not. An indefinite blockade is not a passive equilibrium for Iran. If Washington is going to prevent Iran from exporting its own oil and further squeeze its economy, Tehran has every incentive to demonstrate that this comes with a price. That could mean further attacks on tankers, disruption to regional shipping, or eventually broader retaliation designed to raise the economic and military cost of maintaining the blockade.
So, the nature of the escalation risk has changed rather than disappeared. A deliberate U.S. decision to initiate another major round of military operations looks less likely. But the risk of escalation emerging from the blockade remains significant: Iran increases pressure on shipping or other regional interests, the U.S. responds, Iran retaliates, and both sides find themselves back in an escalatory cycle that neither originally intended.
Going forward, I therefore expect divergent short-term and longer term outcomes. Near term, the risk of deliberate U.S. escalation has fallen, and diplomacy has been given more runway. But the probability of a prolonged and inherently unstable standoff has increased. Unless Washington and Tehran can find a formula that allows both sides to claim some degree of success, the increasingly plausible end-state is an uncomfortable and volatile stalemate, potentially through the remainder of Trump’s term. From a longer term perspective, the U.S. midterm elections have marked the beginning of the end of the war.
Our latest insights
-
-
-
Active Management
-
Defined Contribution
-
Municipal Bonds
RELATED INSIGHTS
Don’t miss out
Get the Capital Ideas newsletter in your inbox every other week