Active Management
 David Hoag
 Harry Phinney
Don't miss our latest insights.
- Treasury supply may keep yields elevated, and after a historic selloff, long-dated Treasuries offer value.
- Markets can likely absorb the additional duration from Treasury and corporate/hyperscaler issuance, though elevated yields may be necessary to attract investors.
- Strong and broadening earnings are setting the stage for credit selectivity.
- Navigating the debt wave calls for flexible and balanced positioning.
Bond issuance has surged as hyperscalers fund the AI infrastructure buildout and the U.S. Treasury continues to borrow. At the same time, war in Iran, rising energy prices, expanding term premiums and potentially weaker demand for new debt have sent yields sharply higher. At the end of September, the 10-year Treasury yield breached 5.3%, a level that many investors had viewed until recently as a tail-risk for the economy, before retreating somewhat in recent weeks.
These pressures raise urgent questions for bond investors. Despite a recent flight to safety spurred by anxiety over hyperscaler debt and AI liabilities, investors are still asking: how high can yields go? And can markets absorb the growing debt burden? While the first question is tough to answer, we believe demand will come through, but not without some caveats. Abundant future supply gives investors little urgency to buy, which may keep yields elevated and produce sharp changes in relative value. In this environment, patience, selectivity and the flexibility to rotate among opportunities across fixed income markets — and to play defense — will be essential.
U.S. debt supply is set to grow
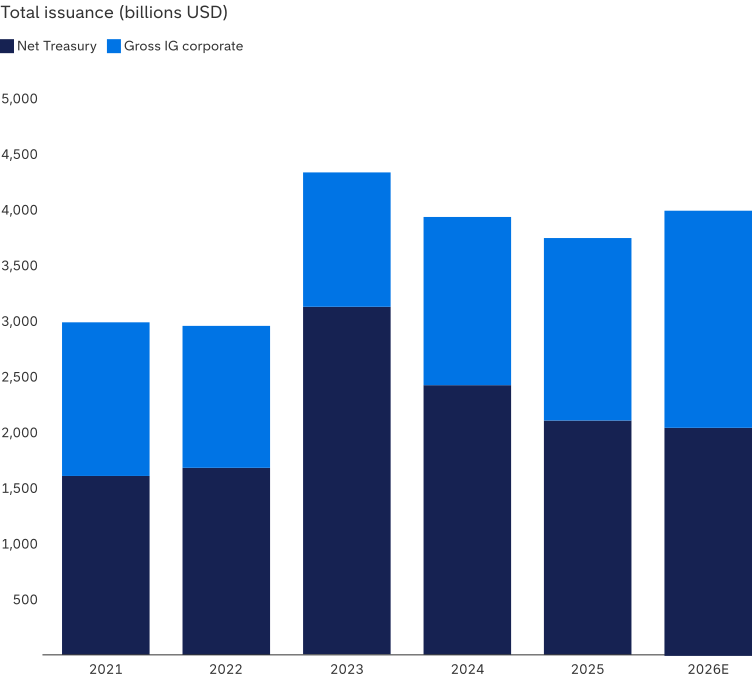
Sources: Capital Group, J.P. Morgan. 2026 Treasury and investment-grade (IG) corporate issuance estimates as of October 2, 2026, and October 5, 2026, respectively. Net Treasury issuance reflects net new Treasury borrowing rather than debt issued to refinance maturing obligations. Treasury issuance reflects debt held by private sector investors, including banks, mutual funds, foreign investors and households.
Treasury supply may keep yields elevated
Heavy Treasury issuance driven by large fiscal deficits and refinancing needs will remain a challenge for bond markets. To help manage rising borrowing costs, the Treasury has issued more shorter dated maturities, limiting the amount of duration the market must absorb at a time when investors are demanding higher compensation to hold long-term debt.

Sources: Capital Group, Bloomberg, U.S. Department of the Treasury, SIFMA. Data shown is monthly from January 2000 through September 2026. Gross issuance represents the total face value of Treasury securities issued before accounting for maturities, redemptions or buybacks. Bills are short-term Treasury securities with maturities of one year or less. Notes are medium-term Treasury securities with maturities of 2–10 years. Bonds are long-term Treasury securities with maturities of 10–30 years.
Foreign demand is an important and uncertain factor. Non-U.S. investors remain major holders of U.S. government debt, but their participation had declined to 40% as of mid-2025, from about 50% of outstanding U.S. Treasury securities during the global financial crisis, according to an August 2026 Brookings report. Thus far the decline has appeared gradual and structural, likely reflecting concerns about U.S. fiscal dynamics but offset by the dollar’s reserve-currency status. A smaller foreign buyer base could require higher yields to attract sufficient demand for new Treasury issuance.
After a historic selloff, long-dated Treasuries offer value
The severe repricing of long-duration bonds has produced historically weak trailing returns, but it has also lifted starting yields, improving their income potential and providing a stronger foundation for future returns. While yields may not have peaked, the starting conditions for long-duration investors have become more favorable.

Sources: Capital Group, Federal Reserve Bank of St. Louis, NYU Stern School of Business. As of October 22, 2026. Treasury bonds are represented by the constant-maturity 10-year U.S. Treasury bond. Annual total returns are estimated from changes in Treasury yields and coupon income. Forward 10-year annualized returns represent the compounded annualized return over the subsequent 10 years.
Persistently high rates and energy costs could eventually weigh on consumption and economic activity, creating scope for yields to decline and long-duration bonds to appreciate. The question for investors, then, is whether, when and how much to allocate to longer dated bonds. With yields potentially rising further in the near term, we favor a measured entry rather than a significant extension of duration.
Strong and broadening earnings set the stage for credit selectivity
Corporate issuance is set to expand in the coming year, driven largely by hyperscalers financing the AI buildout. Markets have so far accommodated that supply, but at a higher cost. Meta-linked data center projects, for example, have raised tens of billions of dollars in recent financings, including a roughly $12.5 billion bond offering for an El Paso campus that priced at about 7.5% — around 40 basis points above a comparable Meta financing completed the previous year. The deal attracted substantial demand, but its higher yield underscored the additional compensation investors require as AI-related debt issuance accelerates.
Corporate fundamentals remain broadly supportive, but historically tight credit spreads suggest a diversified approach to sector and credit quality exposures is likely the most risk-prudent strategy for many investors. Importantly, absolute yield levels remain high across most issues, providing ample opportunities for investors to lock in attractive income. Some AI-related financings offer additional spread, reflecting a combination of heavy supply, financing complexity and uncertainty about future cash flows and funding needs. These risks differ between direct hyperscaler borrowing and project-level debt. Heavy AI-related issuance could also intensify competition for investor capital, potentially raising borrowing costs or influencing the timing and maturity of issuance by other companies.
Against this backdrop, the opportunity set extends well beyond any single group of issuers or market theme. Diversification across corporate credit, Treasuries, securitized credit, agency and non-agency mortgages, and other traditional core sectors can provide multiple sources of income, liquidity and relative value while helping to balance concentrated credit exposure. In our view, heavy issuance and relatively rich valuations make security selection increasingly important, with a preference for issuers with durable cash flows and strong balance sheets along with attractively structured securities, rather than a broad reach for yield.
Flexibility and a focus on relative value can help ride out volatility
In the current environment, with valuations tight and market volatility likely to persist, opportunities are not uniform across fixed income. Investors may benefit from comparing relative value across sectors — remaining selective in credit, seeking attractive income and defensive characteristics in Treasuries and agency mortgage-backed securities (MBS), and actively managing duration as the macro outlook evolves. At a time when U.S. households hold a record-high share of their assets in equities, potentially leaving portfolios more exposed to softer growth and renewed market volatility, this flexibility may be especially valuable.

Sources: Capital Group, Federal Reserve Bank of St. Louis. Latest data available is Q2 2026 as of September 30, 2026. Equities include assets held directly and indirectly through life insurance, private pensions, federal, state and local retirement funds, and mutual funds. Fixed income includes debt securities and loans.
We continue to see value in Treasuries, with higher starting yields having restored a meaningful income opportunity in risk-free assets and may help cushion capital losses if rates rise further. The front and intermediate portions of the curve could be particularly responsive to a less hawkish Fed, weakening consumption or slowing wage growth, while the long end remains more exposed to fiscal concerns and the resulting demand for additional term premium. Agency MBS is another area that appears more compelling than many corporate sectors, with valuations having returned closer to historical norms.
Still, few fixed income areas look unequivocally inexpensive, and heavy issuance could keep producing sharp relative value changes. Investors who can move across sectors and asset classes, including Treasuries, agency MBS and corporate bonds — and adjust duration, credit quality and issuer exposure — may be better positioned to benefit than portfolios tied closely to index weights. Even if valuations remain tight, high yields continue to offer attractive income opportunities. Identifying the best relative value, however, requires deep fundamental research and the flexibility to allocate across sectors.
Duration measures a bond’s sensitivity to changes in interest rates. Generally speaking, a bond's price will go up 1% for every year of duration if interest rates fall by 1% or down 1% for every year of duration if interest rates rise by 1%. When an investor talks about “owning duration,” this means that they have exposure to interest rate risk.
Past results are not predictive of results in future periods.
Our latest insights
-
-
Defined Contribution
-
Municipal Bonds
-
-
Artificial Intelligence
RELATED INSIGHTS
Don’t miss out
Get the Capital Ideas newsletter in your inbox every other week