Markets & Economy
Categories
Election
U.S. midterm impacts on AI data centres, tariffs and Iran
 Matt Miller
 Tom Cooney
 Talha Khan
November 11, 2026
In the aftermath of the U.S. midterm elections, a big blue wave of Democratic Party victories has raised important questions about three critical issues central to the U.S. economy and markets.
How will the coming sea change in American politics affect the artificial intelligence boom, global trade deals and the outcome of the Iran war? The American people have spoken at the ballot box, but how will that sentiment translate into real-world events? Three of Capital Group’s most experienced policy advisors offer their views.
U.S. politics around AI data centres will improve
Matt Miller, political economist
Given the sharp selloff in AI-related stocks last week, you may be surprised to learn that I think the political backlash against data centres will ease, not worsen, in the year ahead. That doesn’t mean there won’t be a lot of noise along the way, and some near-term delays, but my hypothesis is that although the costs of the data centre buildout will rise, the quantity of compute sought will be politically achievable once new leaders settle in to govern.
What leads me to this emerging view? The coalition behind the data centre buildout knows it has fundamentally botched the politics on this issue and is moving aggressively to fix it. Based on what I’ve learned speaking with AI executives, investors and political strategists, it’s clear they are working together to come forward with a new framework of more generous, responsible and transparent offers to communities affected by data centre construction. The commitments may include: no impact on water supply and quality; no impact on utility rates, along with a readiness to throttle energy use if needed at times of peak demand; and appropriate protections against excessive noise and environmental impacts. Beyond that, there may be a need for tax contributions or related investments that assure an unambiguously positive influence on communities.
Four potential paths in the AI data centre buildout story
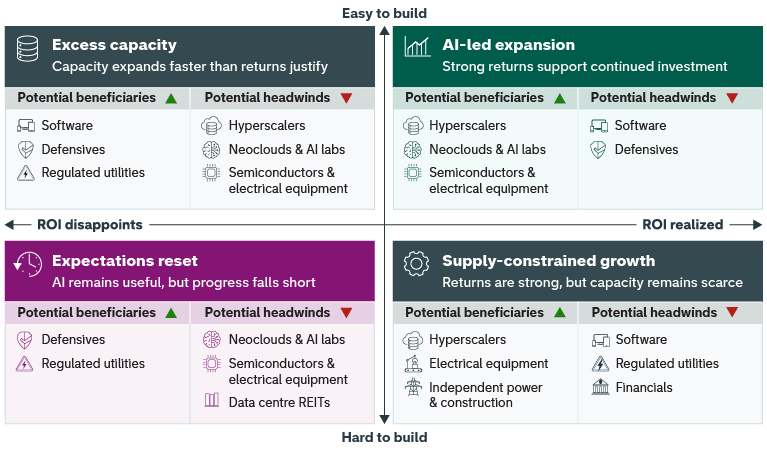
Source: Capital Group. Scenarios reflect analysis of Capital Group’s Night Watch team as of October 2026, and they are not predictive of future outcomes. ROI: return on investment. REITs: real estate investment trusts. Hyperscalers are large-scale cloud service providers that offer computing power and storage to organizations and individuals globally. Neoclouds are specialized cloud infrastructure providers dedicated to AI workloads.
As new benefits from the pro-data centre coalition become clearer, I believe U.S. public opinion will shift. All the pre-election calls for moratoriums have been politically sufficient, yet ultimately flexible, positions for officials of both parties to take as community opposition has risen. It shows U.S. voters they are being heard, but it also leaves the door open for win-win negotiations to proceed in states with new leaders, such as Texas, Ohio and Georgia.
A year from now, I believe this will be a big piece of the data centre construction story. From an elected official’s standpoint, the positioning is excellent. They can show toughness by pushing back against big tech firms that voters don’t trust — and then deliver serious protections and broader community benefits for which they can take credit. This may result in higher costs for AI development. I would urge investors not to overreact to short-term political noise, particularly when you see tech executives called before U.S. Congress or even investigated. Beyond the headlines and given some time for a new political narrative to take shape, the puck is in the process of moving to a better long-term place for the data centre buildout.
U.S. trade leverage waning post-midterms
Tom Cooney, international policy advisor
For the next two years while President Trump remains in the White House, other countries — friend and foe — will be recalculating their relationships and leverage with Washington, D.C. My base case is that we will see more pushback from abroad and even harder bargaining on trade and tariffs, but not a total break with Trump because he can still inflict damage in a trade-war scenario.
China will prioritize “constructive strategic stability” as its primary objective for the next two years, continue de-risking from the U.S., and will not seek any “grand bargain” that could well expire in 2028. Canada, Brazil and India will feel even more emboldened to resist overly generous trade concessions. They would prefer deals and stability, but their leaders will be rewarded at home for hanging tough against Trump.
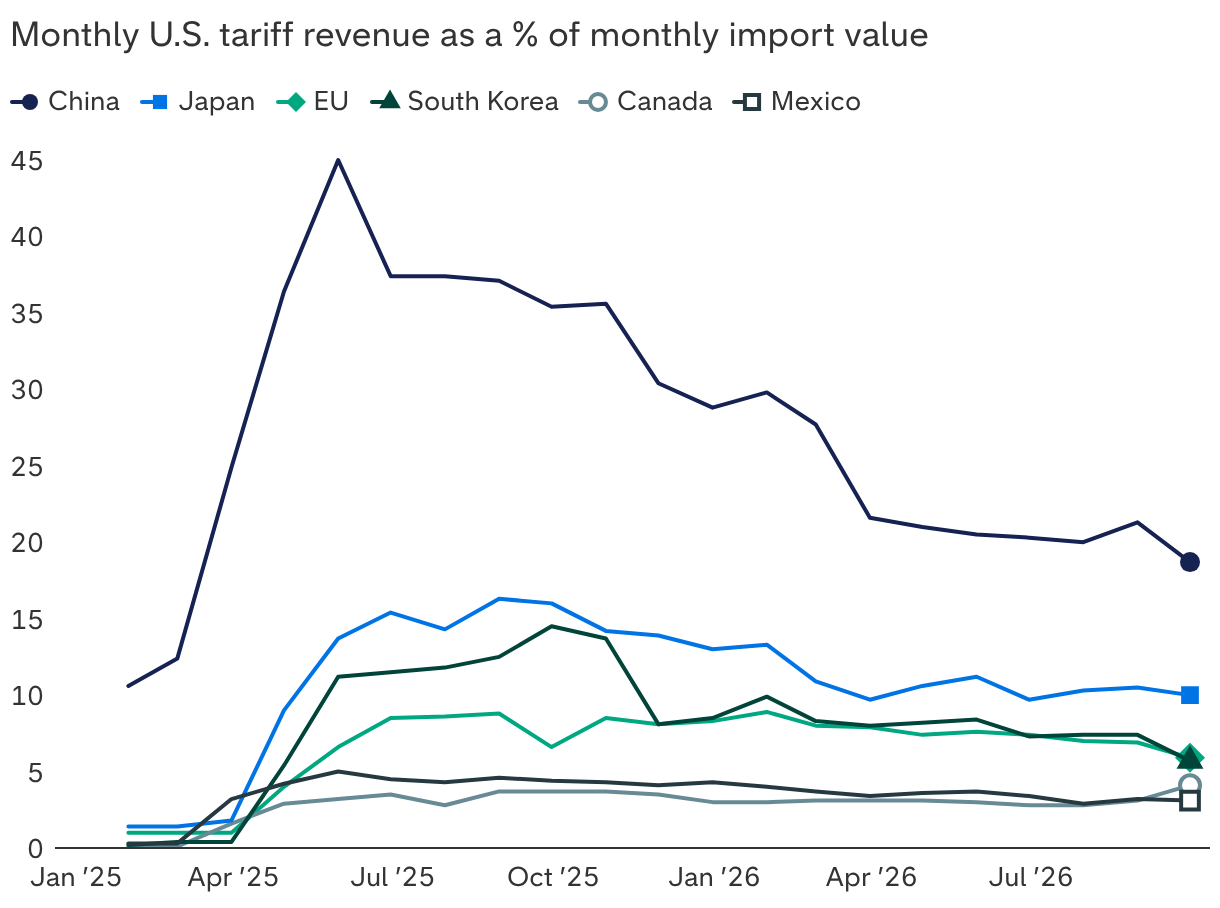
U.S. tariff revenue has declined from its peak early last year
Sources: Capital Group, Peterson Institute for International Economics (PIIE), U.S. International Trade Commission (USITC). Figures reflect PIIE calculations using USITC data. Total import value includes cost, insurance and freight. As of September 30, 2026.
Japan, South Korea and Europe will seek to avoid trade conflict, but I am now even more skeptical than I already was that they will actually deliver anything close to the exorbitant investment levels they agreed to in earlier trade deals with the U.S. They will make some investments in the U.S., of course, because it remains a good place to invest with many viable projects offering good returns. But I would not count on the European Union to deliver anything like the previously agreed $600 billion or Japan to deliver $550 billion by end of 2028, for example.
In my view, the lesson from the U.S. midterm elections, as well as the 2024 general election, is that the American public is taking turns punishing political parties for their failure to deliver what matters most — fixing problems at home of inflation, affordability and economic opportunity. The 2024 election did not signal a permanent right-wing realignment, nor does last week’s “blue tsunami” signal the same for left-leaning political leadership. Neither party owns the electorate, and American voters are identifying less with either party.
The only certainty is that we are nearing the end of the Trump era, and he will resist losing primacy as he now must contend with a Democratic Congress. This dynamic sets the stage for further contention and volatility ahead. I expect President Trump will be more restrained than ever domestically by the courts and Congress, so this will cause him — like many U.S. presidents in the final two years of the second term — to lean into foreign policy where he has more leeway, as well as legacy projects seeking to leave his physical mark on Washington landmarks.
Ending the Iran war won’t be easy or quick
Talha Khan, political economist
The U.S. midterms have reduced the immediate risk of another American attack on Iran, but they may have made the war harder to end. The political costs of renewed escalation have risen for President Trump, making it more attractive to maintain economic and military pressure while giving diplomacy more time. But the election has also complicated the search for an exit. Washington and Tehran remain locked in a game of cat and mouse. Neither side wants to offer concessions that could hand the other a strategic victory. The problem, as always, is not whether both sides ultimately want an exit, but how we get there.
What has changed this week is the immediate risk of deliberate U.S. escalation. That risk has fallen, but it is certainly not zero. Following Trump’s conversation with the Qatari prime minister, another round of U.S. strikes no longer appears to be the immediate base case. Trump has explicitly kept the military option open, but for now appears to have concluded that the uncertain benefits of another round of strikes do not justify the military, economic and political costs.
Instead, Trump appears to have chosen economic pressure over military escalation, at least for now. The launch of “Operation Iron Gate” points to an effort to tighten the Iran blockade further, constrain its ability to export oil and allow that pressure to accumulate, while keeping substantial U.S. military power in the region as a credible threat. That also buys more time for diplomacy. If talks progress, Trump can argue that maximum pressure forced Tehran back to the table. If they fail, the military option remains available.
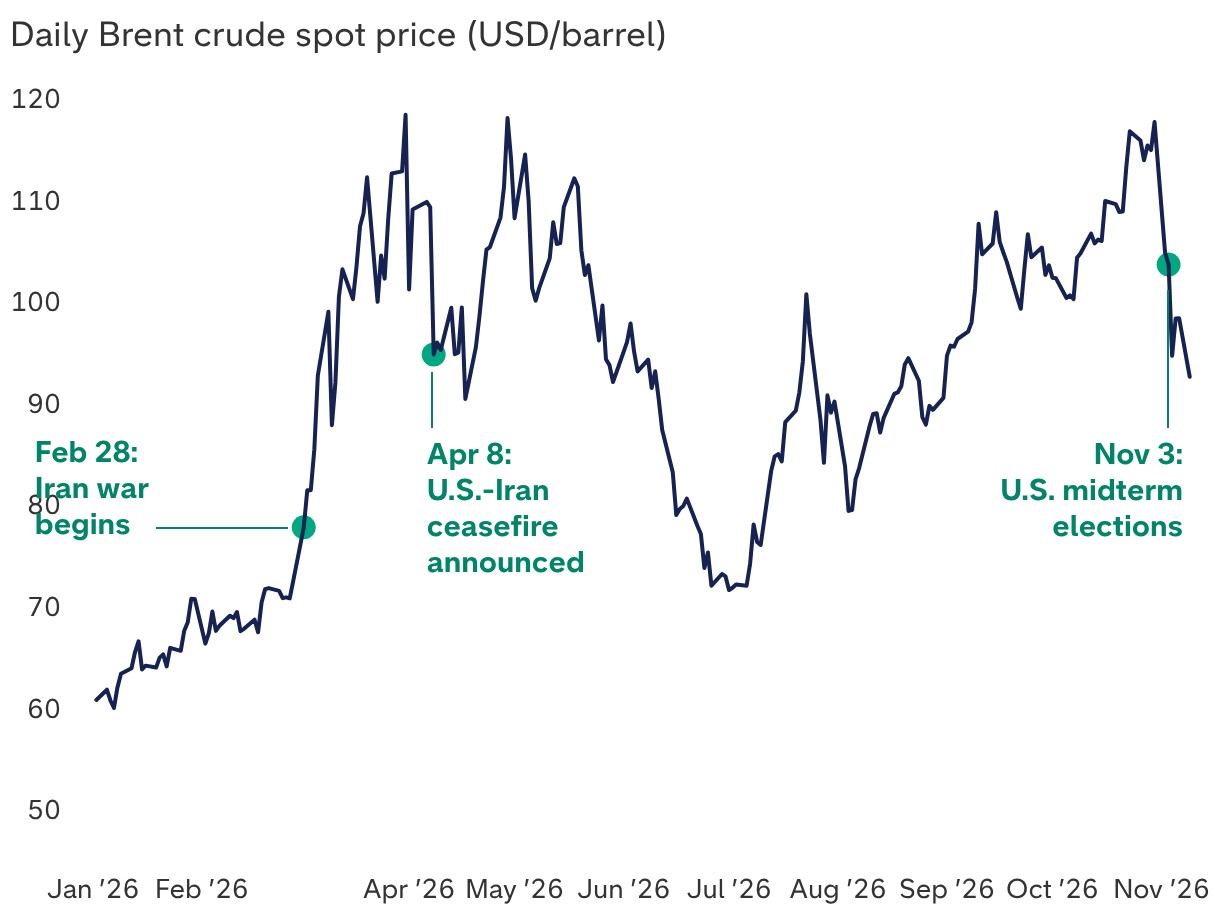
The U.S.-Iran conflict has sparked a sharp rise in oil prices
Sources: Capital Group, Bloomberg, ICE, Reuters. As of November 9, 2026. Values in USD.
However, the absence of an immediate U.S. strike should not be confused with de-escalation. Iran’s response since Trump’s announcement suggests very little willingness to soften its existing negotiating position. If anything, the midterms appear to have strengthened Tehran’s belief that time is working in its favour. Iran does not need to defeat the U.S. militarily if it can survive, refuse to capitulate and impose enough economic and political costs that Washington eventually loses the appetite to continue.
That creates a central problem: Washington may prefer the status quo, but Tehran does not. An indefinite blockade is not a passive equilibrium for Iran. If Washington is going to prevent Iran from exporting its own oil and further squeeze its economy, Tehran has every incentive to demonstrate that this comes with a price. That could mean further attacks on tankers, disruption to regional shipping, or eventually broader retaliation designed to raise the economic and military cost of maintaining the blockade.
So, the nature of the escalation risk has changed rather than disappeared. A deliberate U.S. decision to initiate another major round of military operations looks less likely. But the risk of escalation emerging from the blockade remains significant: Iran increases pressure on shipping or other regional interests, the U.S. responds, Iran retaliates, and both sides find themselves back in an escalatory cycle that neither originally intended.
Going forward, I therefore expect divergent short-term and longer term outcomes. Near term, the risk of deliberate U.S. escalation has fallen, and diplomacy has been given more runway. But the probability of a prolonged and inherently unstable standoff has increased. Unless Washington and Tehran can find a formula that allows both sides to claim some degree of success, the increasingly plausible end-state is an uncomfortable and volatile stalemate, potentially through the remainder of Trump’s term. From a longer term perspective, the U.S. midterm elections have marked the beginning of the end of the war.
Learn more about
Our latest insights
-
-
-
Portfolio Construction
-
Technology & Innovation
-
Objective-Based Investing
RELATED INSIGHTS
-
-
Artificial Intelligence
-
Portfolio Construction
Commissions, trailing commissions, management fees and expenses all may be associated with investments in investment funds. Please read the prospectus before investing. Investment funds are not guaranteed or covered by the Canada Deposit Insurance Corporation or by any other government deposit insurer. For investment funds other than money market funds, their values change frequently. For money market funds, there can be no assurances that the fund will be able to maintain its net asset value per security at a constant amount or that the full amount of your investment in the fund will be returned to you. Past performance may not be repeated.
Unless otherwise indicated, the investment professionals featured do not manage Capital Group‘s Canadian investment funds.
References to particular companies or securities, if any, are included for informational or illustrative purposes only and should not be considered as an endorsement by Capital Group. Views expressed regarding a particular company, security, industry or market sector should not be considered an indication of trading intent of any investment funds or current holdings of any investment funds. These views should not be considered as investment advice nor should they be considered a recommendation to buy or sell.
Statements attributed to an individual represent the opinions of that individual as of the date published and do not necessarily reflect the opinions of Capital Group or its affiliates. This information is intended to highlight issues and not be comprehensive or to provide advice. For informational purposes only; not intended to provide tax, legal or financial advice. Capital Group funds are available in Canada through registered dealers. For more information, please consult your financial and tax advisors for your individual situation.
Forward-looking statements are not guarantees of future performance, and actual events and results could differ materially from those expressed or implied in any forward-looking statements made herein. We encourage you to consider these and other factors carefully before making any investment decisions and we urge you to avoid placing undue reliance on forward-looking statements.
The S&P 500 Composite Index (“Index”) is a product of S&P Dow Jones Indices LLC and/or its affiliates and has been licensed for use by Capital Group. Copyright © 2026 S&P Dow Jones Indices LLC, a division of S&P Global, and/or its affiliates. All rights reserved. Redistribution or reproduction in whole or in part are prohibited without written permission of S&P Dow Jones Indices LLC.
FTSE source: London Stock Exchange Group plc and its group undertakings (collectively, the "LSE Group"). © LSE Group 2026. FTSE Russell is a trading name of certain of the LSE Group companies. "FTSE®" is a trade mark of the relevant LSE Group companies and is used by any other LSE Group company under licence. All rights in the FTSE Russell indices or data vest in the relevant LSE Group company which owns the index or the data. Neither LSE Group nor its licensors accept any liability for any errors or omissions in the indices or data and no party may rely on any indices or data contained in this communication. No further distribution of data from the LSE Group is permitted without the relevant LSE Group company's express written consent. The LSE Group does not promote, sponsor or endorse the content of this communication. The index is unmanaged and cannot be invested in directly.
BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg or Bloomberg’s licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg’s licensors approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
The MSCI information may only be used for your internal use, may not be reproduced or redisseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to compiling, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages. (www.msci.com)
Capital believes the software and information from FactSet to be reliable. However, Capital cannot be responsible for inaccuracies, incomplete information or updating of the information furnished by FactSet. The information provided in this report is meant to give you an approximate account of the fund/manager's characteristics for the specified date. This information is not indicative of future Capital investment decisions and is not used as part of our investment decision-making process.
Indices are unmanaged and cannot be invested in directly. Returns represent past performance, are not a guarantee of future performance, and are not indicative of any specific investment.
All Capital Group trademarks are owned by The Capital Group Companies, Inc. or an affiliated company in Canada, the U.S. and other countries. All other company names mentioned are the property of their respective companies.
Capital Group funds are offered in Canada by Capital International Asset Management (Canada), Inc., part of Capital Group, a global investment management firm originating in Los Angeles, California in 1931. Capital Group manages equity assets through three investment groups. These groups make investment and proxy voting decisions independently. Fixed income investment professionals provide fixed income research and investment management across the Capital organization; however, for securities with equity characteristics, they act solely on behalf of one of the three equity investment groups.
The Capital Group funds offered on this website are available only to Canadian residents.