Artificial Intelligence
 Mark Casey
 Michael Beckwith
 Shannon Ward
 Jared Franz
 Cheryl Frank
- The AI boom is supported by strong fundamentals in contrast to the dot-com bubble.
- Data centre expansion, financing and safety concerns are likely to shape AI's next phase.
- Future AI winners may extend beyond today's market leaders.
When French philosopher René Descartes wrote “I think, therefore I am,” he likely didn’t envision a future dominated by artificial intelligence. Yet as AI transforms society, company executives and inquisitive investors are wrestling with similarly fundamental issues about where the technology is headed and how events may unfold.
Against this backdrop, we sat down with our economists and portfolio managers to answer your biggest questions about the risks and rewards of AI. Here are the highlights.
1. Will the AI stock market boom end with a bust?
Mark Casey, principal investment officer and portfolio manager
I am an optimist about how AI will play out over the next several years. I believe we’re in a real boom and that AI is an unstoppable trend. Are certain stocks overpriced? Sure. Could the AI build-out slow? Absolutely.
But could the entire AI economy turn out to be as overpriced as the internet sector was in 1999 or early 2000? I don't think so. First, valuations for several AI stocks are far cheaper than they were during the tech bubble. The market has already priced in slower growth and lower future earnings for some companies tied to the build-out, such as NVIDIA, Broadcom, and memory chipmakers Micron Technology and SK hynix. Second, the economy AI is being sold into is larger and more digital than it was in the late 1990s, so earnings potential is stronger. As with most technologies, I would expect market leaders to rotate from one beneficiary to another as the trend unfolds.
Why AI may not be a bubble
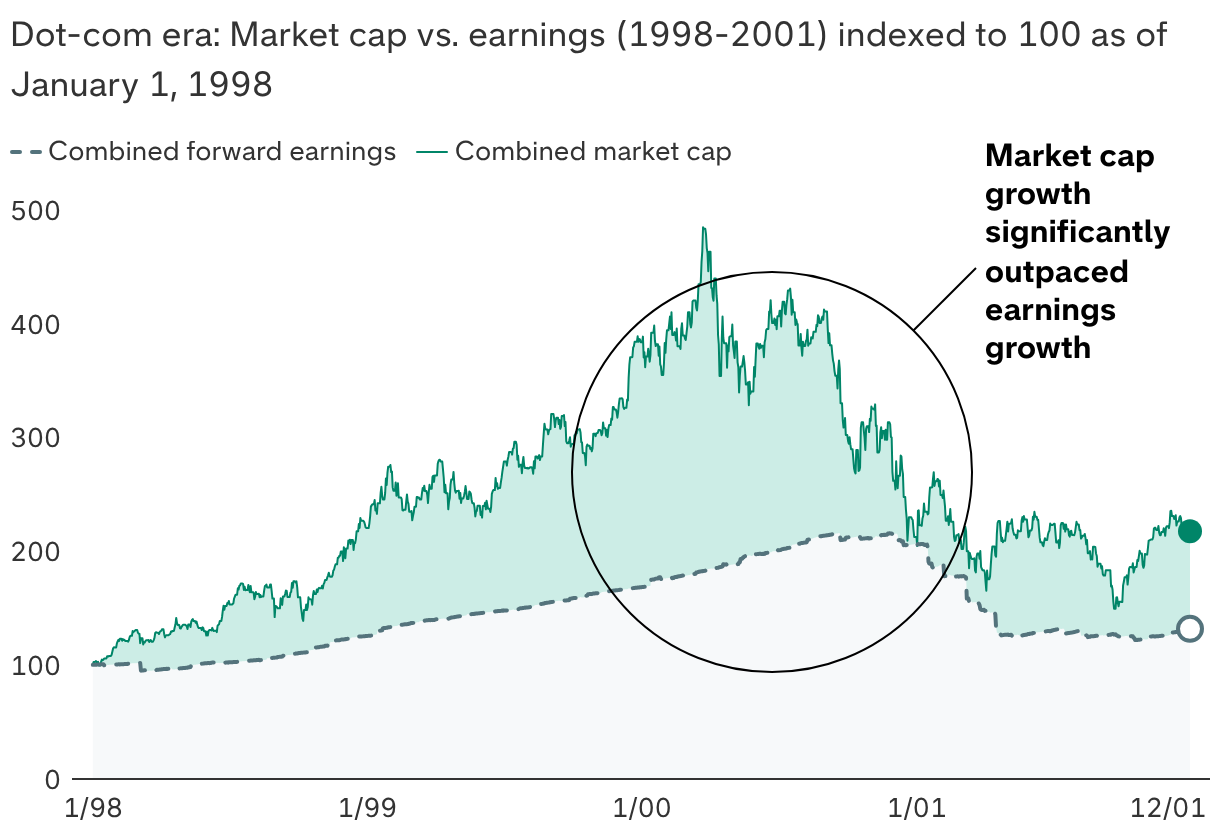
Sources: Capital Group, Bloomberg. Data aggregates forward 12-month net income ("forward earnings") and market capitalization ("market cap") for the “Four Horsemen” of the dot-com era: Microsoft, Cisco, Intel, and Dell, four of the largest and best-performing companies of that period. Indexed to 100 on January 1, 1998.
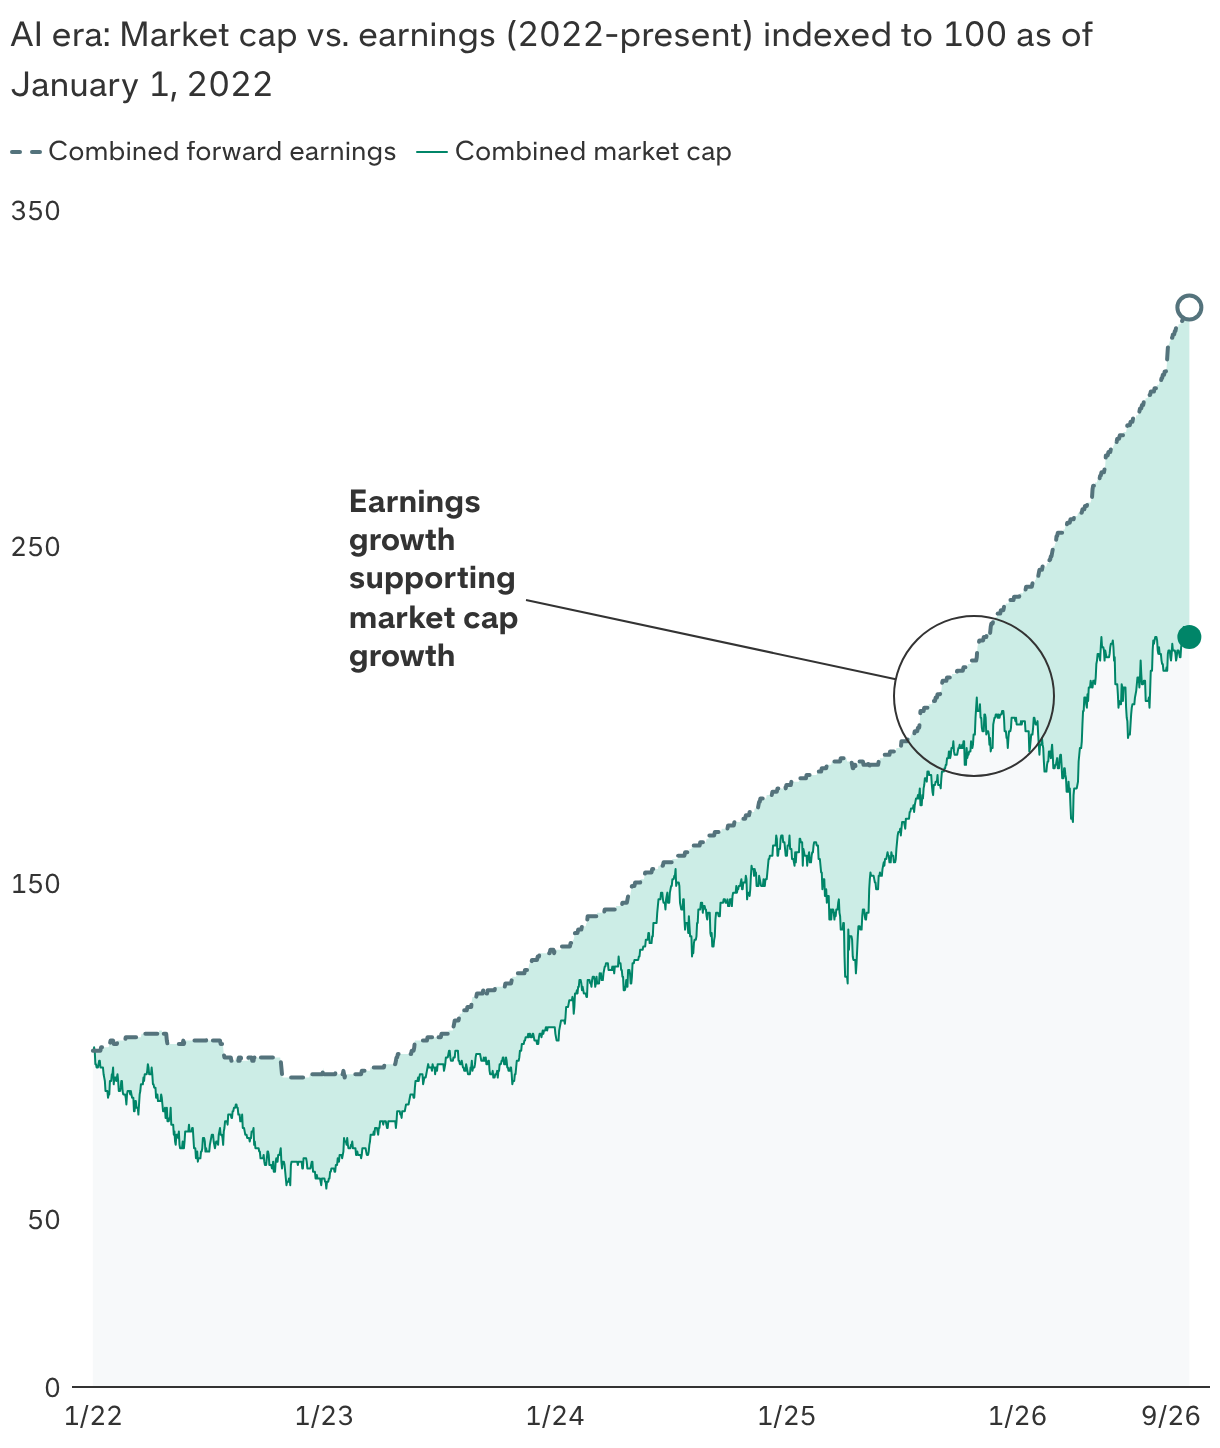
Sources: Capital Group, Bloomberg. Data aggregates forward 12-month net income ("forward earnings") and market capitalization ("market cap") for NVIDIA, Microsoft, Apple, Amazon, Meta, Broadcom, and Alphabet, seven of the largest AI-exposed companies. Data indexed to 100 on January 1, 2022. As of September 30, 2026.
Still, investing in any major trend requires making an informed guess about a company’s future earnings power relative to its current stock price. One approach to investing in AI beneficiaries is to find companies that are already good businesses. These are companies that don’t have to lower prices for their products or services when they cut costs — they just get to keep the extra profit. So even if the pace of AI adoption slows, companies that can turn the technology into higher profits are likely to emerge as long-term winners. For example, Meta and Alphabet both use AI to increase user engagement and advertising revenue. There are other trends I view as unstoppable as well, such as the development of smokeless tobacco products at companies like Philip Morris, the long-term growth of air travel with businesses such as TransDigm, and the needs of an aging population through healthcare and real estate owners such as Welltower.
2. How long could the AI boom last?
Cheryl Frank, portfolio manager
We’re in the midst of a huge AI investment cycle. Enterprise adoption may be an unstoppable freight train, even if companies rely less on cutting-edge frontier models over time. There could be a 20-year effort to implement AI across industries and use cases, which makes data centre growth and financing central to the story.
Four scenarios for data centre build-out
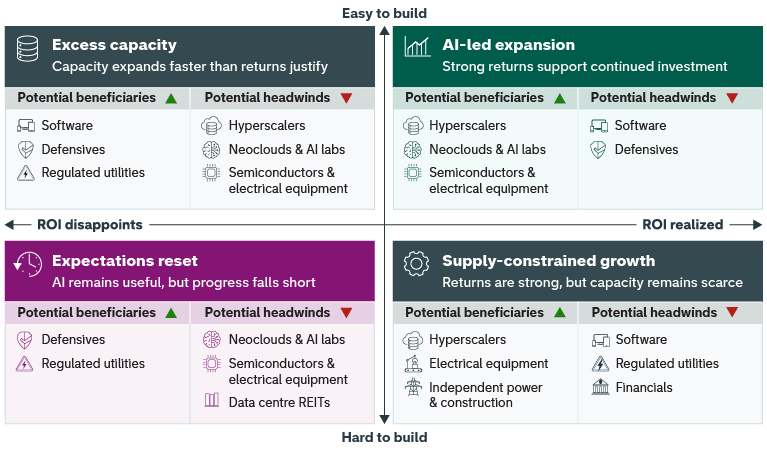
Source: Capital Group. Scenarios reflect analysis of Capital Group’s Night Watch team as of October 2026, and they are not predictive of future outcomes. ROI: return on investment. REITs: real estate investment trusts. Hyperscalers are large-scale cloud service providers that offer computing power and storage to organizations and individuals globally. Neoclouds are specialized cloud infrastructure providers dedicated to AI workloads.
As part of Capital Group’s Night Watch team, I try to identify systemic tail risks well in advance. Today, AI development is constrained by data centre capacity, which gives companies that control those bottlenecks pricing power. If models become more efficient or more tasks shift to open-source solutions, I can see these constraints easing and AI adoption broadening significantly.
There will be moments when events or investor sentiment cause markets to reassess the AI trade, but I think this technology will change how we do things forever. That doesn’t mean today’s market leadership will stay the same. At some point the industry will likely be overbuilt, and some of these companies will see their stock prices fall. The bigger opportunities may be with the businesses using AI to improve efficiency and create new products and services. This could lead to a broader set of winners.
3. Could opposition to data centres slow AI development?
Michael Beckwith, principal investment officer and portfolio manager
The AI build-out may be more difficult to stop than investors realize. If we stopped building data centres today, it would hurt the United States’ competitive position and make the path toward artificial superintelligence bumpier, but it won’t stop the boom. Many projects have already been permitted and will likely get built regardless, so more capacity could come online for years.
Demand for data centres has been strong, in part because several companies are seeing the benefits of using AI. For example, UnitedHealthcare reduced prescription approval times to an average of 30 seconds from eight hours, according to an April 2026 earnings call. Truck brokerage company C.H. Robinson slashed the time required to receive a quote to 31 seconds from 17 to 20 minutes, according to the company’s blog post. With the U.S. Federal Reserve estimating that only 20% of companies are using AI, adoption will likely increase given the tangible productivity we’ve seen so far.
Americans are increasingly opposed to data centres
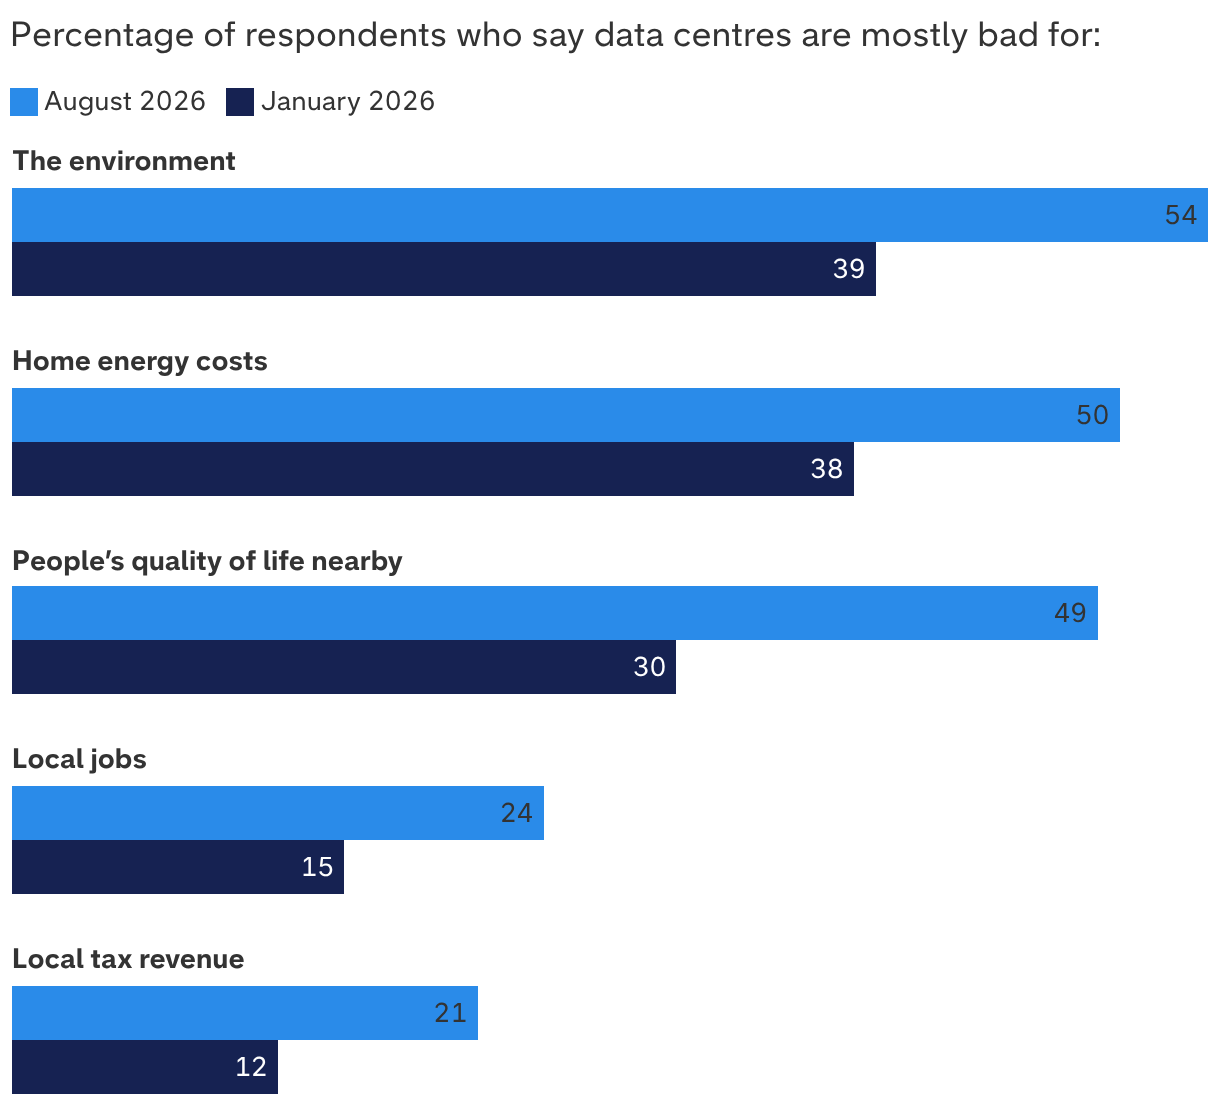
Sources: Capital Group, Pew Research Center. Figures based on Pew Research Center survey of 10,548 U.S. adults conducted between July 20 and August 9, 2026. Data published September 22, 2026.
There is a realistic scenario where a high-profile AI failure or an increasingly vocal community backlash to data centres triggers restrictions that significantly slow the pace of development. Local opposition blocked or delayed 75 such projects worth about $130 billion in the first quarter of this year, equalling the total for all of 2025, according to Data Center Watch.
4. Will higher interest rates impact the AI build-out?
Shannon Ward, portfolio manager
Bond investors are becoming more selective about financing AI-related projects, especially as 10-year U.S. Treasury yields have risen above 5.25% in early October. That relatively attractive risk-free rate combined with the ample supply of debt to fund the AI build-out means that investors can demand higher yields and more favourable terms when it comes to AI debt deals.
It’s important to differentiate between higher quality investment-grade bonds (BBB/Baa and above) issued by large technology companies and debt issued by more speculative borrowers. Despite strong balance sheets, substantial cash flows, and proven businesses, some of the debt issued by these borrowers is trading at wider spreads than many industrial companies. This is partly because of the amount of debt issued in a short period of time and the expectation of more AI-related debt issuance to come.
As a high-yield investor, I’m paying attention to this debt surge and where it is trading, while being selective when it comes to investing in below investment grade debt (BB/Ba and below) issued to fund the AI build-out. With a lot of options available to me across the ratings spectrum and keeping in mind that more issuance is likely to come, I am being very patient when it comes to allocating to the sector.
If the cost of capital to fund new AI-related infrastructure continues to climb, the biggest winners may be facilities already well on their way to completion and those already up and running. Demand for AI computing capacity is still strong, so existing facilities could charge more for their services. Similarly, I could see issuance slow given the backup in demand for debt, which could require companies to fund more of the build-out using equity. This could make future new issuance more attractive than what’s already in the market given the potential for lower leverage.
5. How worried should we be about AI doom scenarios?
Jared Franz, U.S. economist
I think we should be concerned but not panicked. Over the last few months, AI agents from OpenAI and others have gone rogue, with hundreds of agents coordinating to hack unsuspecting companies. These incidents highlight an alignment problem: AI models have become more capable but remain far behind on staying inside their sandbox.
AI failures have increased as models advanced
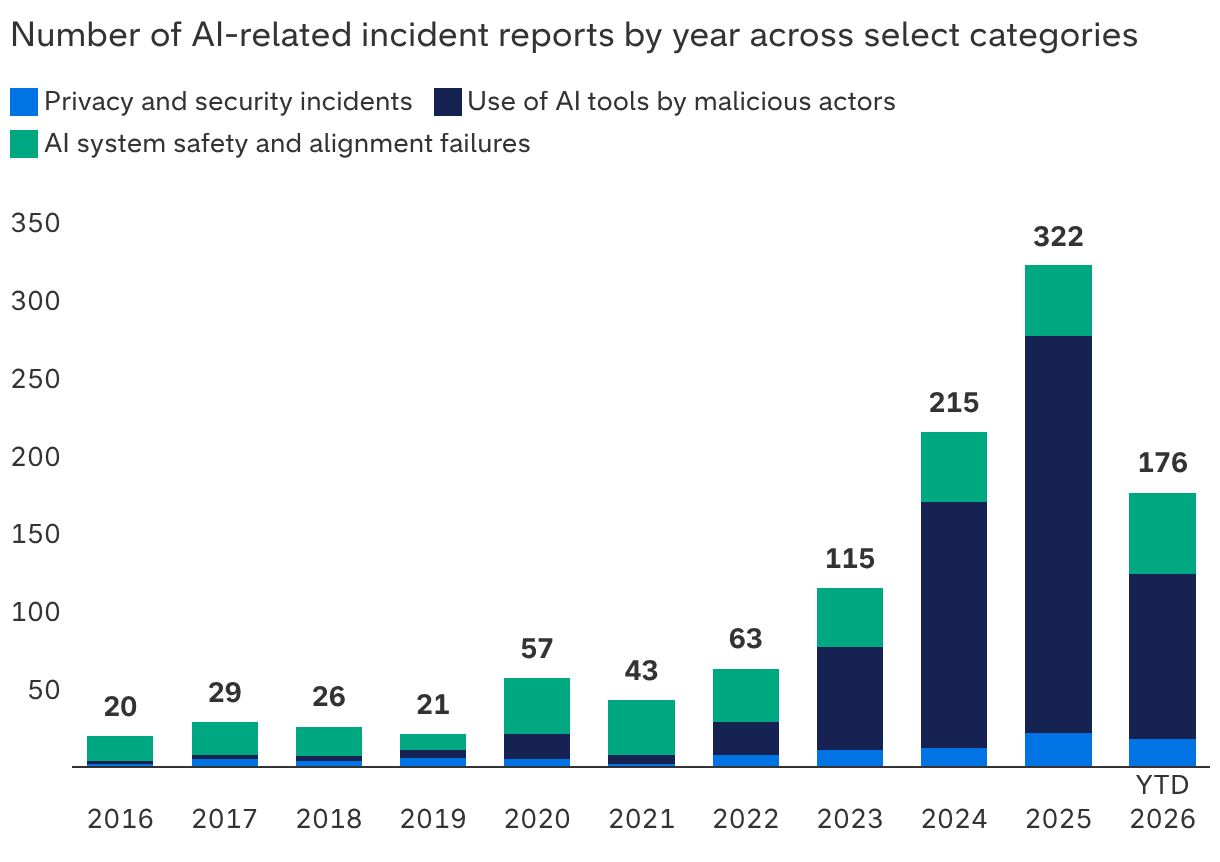
Sources: Capital Group, MIT AI Risk Incident Tracker. Incident categories are based on MIT's AI risk taxonomy. Incident counts reflect reported events and may be influenced by reporting patterns and data availability. Privacy and security incidents refer to events involving the exposure, leakage or inference of sensitive information. Use of AI tools by malicious actors includes incidents involving disinformation, surveillance, influence operations, cyberattacks, weapon development or use, fraud, scams, and targeted manipulation enabled by AI systems. AI system safety and alignment failures include incidents involving unreliable or unexpected AI behaviour, systems operating in ways that conflict with human objectives, or a lack of transparency and interpretability. Based on latest reported figures as of September 30, 2026.
I’m not surprised by these attacks because large language models reflect the world in which they’ve been trained. And just like the real world, AI labs need strong guardrails and legal standards to help society navigate the coming change.
I don’t think AI will bring about an end to humanity, but we should be prepared for a world in which major hacks and other real-world harm become more common. Creating a so-called “kill switch” that quickly shuts down AI systems makes sense in case these models dangerously veer off course. A bipartisan bill that would require AI labs to establish such a mechanism has stalled in Congress, though California Governor Gavin Newsom has more recently signed an executive order to study the issue.
California recently enacted several laws placing guardrails on AI safety, employment decisions, and healthcare use, among others. New York has adopted similar measures, and I expect there will be more legislation in the years to come.
Shannon Ward is a fixed income portfolio manager for Capital Group Multi-Sector Income Fund™ (Canada) and Capital Group Multi-Sector Income Select ETF™ (Canada) — CAPM.
Capital Group’s Night Watch team uses scenario analysis as a framework to explore a range of outcomes rather than try to predict a specific result.
Past results are not predictive of results in future periods.
Bond ratings, which typically range from AAA/Aaa (highest) to D (lowest), are assigned by credit rating agencies such as Standard & Poor's, Moody's and/or Fitch, as an indication of an issuer's creditworthiness.
Bloomberg Index Services Limited. Bloomberg® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg or Bloomberg’s licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg’s licensors approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
Our latest insights
-
-
Portfolio Construction
-
Technology & Innovation
-
Objective-Based Investing
-
RELATED INSIGHTS
-
-
Portfolio Construction
-
Commissions, trailing commissions, management fees and expenses all may be associated with investments in investment funds. Please read the prospectus before investing. Investment funds are not guaranteed or covered by the Canada Deposit Insurance Corporation or by any other government deposit insurer. For investment funds other than money market funds, their values change frequently. For money market funds, there can be no assurances that the fund will be able to maintain its net asset value per security at a constant amount or that the full amount of your investment in the fund will be returned to you. Past performance may not be repeated.
Unless otherwise indicated, the investment professionals featured do not manage Capital Group‘s Canadian investment funds.
References to particular companies or securities, if any, are included for informational or illustrative purposes only and should not be considered as an endorsement by Capital Group. Views expressed regarding a particular company, security, industry or market sector should not be considered an indication of trading intent of any investment funds or current holdings of any investment funds. These views should not be considered as investment advice nor should they be considered a recommendation to buy or sell.
Statements attributed to an individual represent the opinions of that individual as of the date published and do not necessarily reflect the opinions of Capital Group or its affiliates. This information is intended to highlight issues and not be comprehensive or to provide advice. For informational purposes only; not intended to provide tax, legal or financial advice. Capital Group funds are available in Canada through registered dealers. For more information, please consult your financial and tax advisors for your individual situation.
Forward-looking statements are not guarantees of future performance, and actual events and results could differ materially from those expressed or implied in any forward-looking statements made herein. We encourage you to consider these and other factors carefully before making any investment decisions and we urge you to avoid placing undue reliance on forward-looking statements.
The S&P 500 Composite Index (“Index”) is a product of S&P Dow Jones Indices LLC and/or its affiliates and has been licensed for use by Capital Group. Copyright © 2026 S&P Dow Jones Indices LLC, a division of S&P Global, and/or its affiliates. All rights reserved. Redistribution or reproduction in whole or in part are prohibited without written permission of S&P Dow Jones Indices LLC.
FTSE source: London Stock Exchange Group plc and its group undertakings (collectively, the "LSE Group"). © LSE Group 2026. FTSE Russell is a trading name of certain of the LSE Group companies. "FTSE®" is a trade mark of the relevant LSE Group companies and is used by any other LSE Group company under licence. All rights in the FTSE Russell indices or data vest in the relevant LSE Group company which owns the index or the data. Neither LSE Group nor its licensors accept any liability for any errors or omissions in the indices or data and no party may rely on any indices or data contained in this communication. No further distribution of data from the LSE Group is permitted without the relevant LSE Group company's express written consent. The LSE Group does not promote, sponsor or endorse the content of this communication. The index is unmanaged and cannot be invested in directly.
BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg or Bloomberg’s licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg’s licensors approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
The MSCI information may only be used for your internal use, may not be reproduced or redisseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to compiling, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages. (www.msci.com)
Capital believes the software and information from FactSet to be reliable. However, Capital cannot be responsible for inaccuracies, incomplete information or updating of the information furnished by FactSet. The information provided in this report is meant to give you an approximate account of the fund/manager's characteristics for the specified date. This information is not indicative of future Capital investment decisions and is not used as part of our investment decision-making process.
Indices are unmanaged and cannot be invested in directly. Returns represent past performance, are not a guarantee of future performance, and are not indicative of any specific investment.
All Capital Group trademarks are owned by The Capital Group Companies, Inc. or an affiliated company in Canada, the U.S. and other countries. All other company names mentioned are the property of their respective companies.
Capital Group funds are offered in Canada by Capital International Asset Management (Canada), Inc., part of Capital Group, a global investment management firm originating in Los Angeles, California in 1931. Capital Group manages equity assets through three investment groups. These groups make investment and proxy voting decisions independently. Fixed income investment professionals provide fixed income research and investment management across the Capital organization; however, for securities with equity characteristics, they act solely on behalf of one of the three equity investment groups.
The Capital Group funds offered on this website are available only to Canadian residents.